Small business owners juggle five financial systems that were never designed to talk to each other: bookkeeping, payroll, tax prep, retirement plan administration, and investment management. This comparison looks at where a fee-only financial advisor, QuickBooks Online, Gusto, Guideline, TurboTax Business, and spreadsheet templates fit; it is not a ranking.
- A fee-only financial advisor can coordinate household planning with an owner's CPA and attorney; this comparison is about fit, not ranking.
- QuickBooks Online handles daily bookkeeping but has no retirement or investment guidance built in.
- Guideline is the practical choice for setting up a company 401(k) once you're ready to offer one.
- Spreadsheet templates work for very early-stage businesses but become a liability once revenue and complexity grow.
Why this matters
Most small business owners solve financial planning one tool at a time — an accountant for taxes, a payroll processor for staff, and a separate 401(k) provider if they get around to it. That approach works until the business grows past a certain point, and then the gaps between those systems start costing real money in missed tax strategy and poorly coordinated retirement contributions.
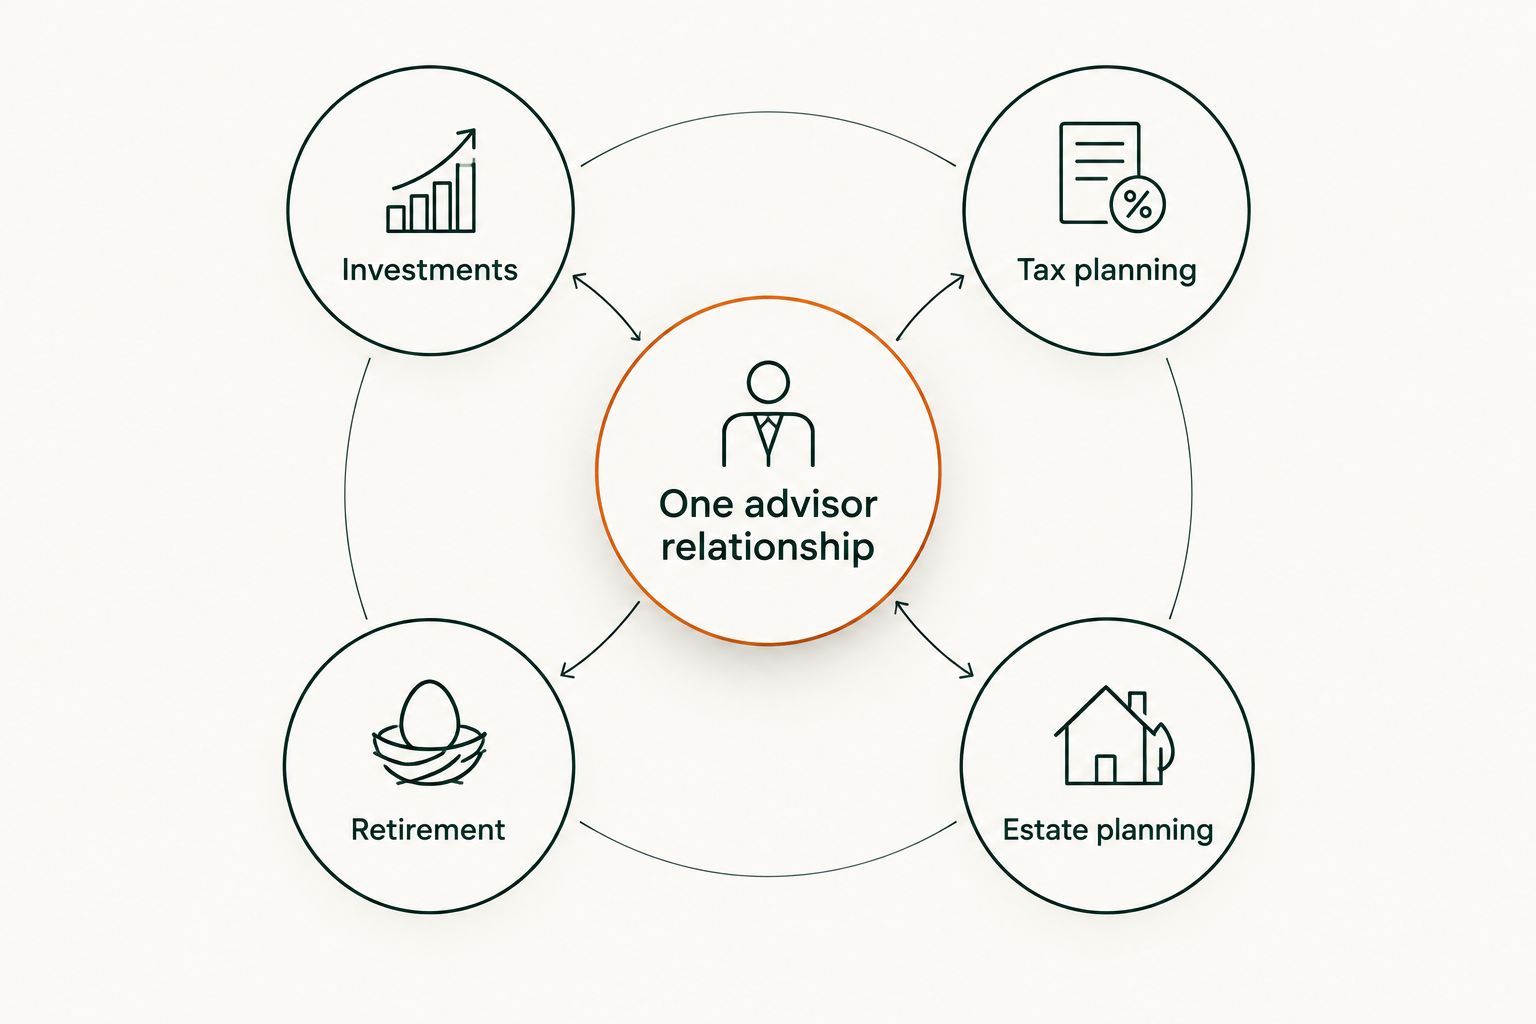
Owners with significant assets tied up in the business and outside investments need someone looking at wealth management strategies built for business owners, not just a piece of software that logs transactions. The tools below split into two camps: software that automates a single function, and a fee-only fiduciary relationship that coordinates all of them. Knowing which camp you actually need in 2026 saves months of redundant work.
What makes the best financial planning tools for small business owners
- Integration — does it connect to your other financial systems, or does it operate in isolation?
- Fiduciary standard — for advisory relationships, is the provider legally required to act in your interest, or just suited to sell you a product?
- Compliance coverage — does it handle nondiscrimination testing, payroll tax filings, or other regulatory requirements automatically?
- Scalability — does it still work when the business doubles headcount or revenue?
- Time saved — does it remove manual work, or just relocate it to a spreadsheet?
At a glance: comparing the top options for 2026
| Tool | Best for | Standout feature | Key limitation |
|---|---|---|---|
| Fee-only financial advisor | For an owner, that can mean one professional reviewing how a retirement contribution, a business sale or an investment decision fits the household plan, in coordination with the owner's CPA and attorney. | A fee-only fiduciary advisor is paid by clients, not by product commissions, and must act in the client's best interest. | Considerations: advisory fees are higher than a software subscription; an advisor does not replace bookkeeping, payroll or tax-return preparation; and minimums vary by firm. |
| QuickBooks Online | Day-to-day bookkeeping | Bank feed reconciliation and cash flow reports | No retirement or investment guidance |
| Gusto | Payroll and benefits | Automated payroll tax filing | Doesn't touch retirement plan design or investments |
| Guideline | Setting up a company 401(k) | Low-maintenance plan administration and auto-enrollment | Investment menu limited to the plan's fund lineup |
| TurboTax Business | Filing a straightforward business return | Guided federal and state interview | No forward-looking tax planning |
| Spreadsheet templates | Very early-stage businesses tracking cash by hand | No subscription, full control of categories | Manual entry, no compliance testing, easy to miss errors |
Fee-only financial advisor
A fee-only fiduciary advisor is paid by clients, not by product commissions, and must act in the client's best interest. For an owner, that can mean one professional reviewing how a retirement contribution, a business sale or an investment decision fits the household plan, in coordination with the owner's CPA and attorney. Considerations: advisory fees are higher than a software subscription; an advisor does not replace bookkeeping, payroll or tax-return preparation; and minimums vary by firm.
QuickBooks Online: best financial planning tool for daily bookkeeping
QuickBooks Online automates the transaction-level work every business needs: bank feed reconciliation, invoicing, expense categorization, and basic financial reports. It's the layer that feeds accurate numbers to everyone else — your CPA, your payroll provider, and any advisor doing higher-level planning.
QuickBooks Online pros:
- Automatic bank and credit card feed syncing
- Standard reports (profit and loss, balance sheet) generated without manual formulas
- Widely used, so most CPAs and bookkeepers already know it
QuickBooks Online cons:
- No retirement account or investment guidance whatsoever
- Add-ons for payroll and advanced reporting can get complicated fast
Best for: any business owner who needs clean, current books without hiring a full-time bookkeeper.
Gusto: best financial planning tool for payroll and benefits
Gusto runs payroll, calculates and files payroll taxes, and administers benefits enrollment for small teams. It exists to remove the single biggest compliance headache new employers face: getting payroll tax withholding and filings right every pay period.
Gusto pros:
- Automated federal and state payroll tax filing
- Handles W-2 and 1099 issuance at year-end
- Benefits administration bundled with payroll in one system
Gusto cons:
- No retirement plan design or investment features — you'll need a separate provider for that
- Doesn't offer tax planning beyond payroll compliance
Best for: owners who've just hired their first W-2 employee and need payroll handled correctly from day one.
Guideline: best financial planning tool for setting up a 401(k)
Guideline administers 401(k) plans for small businesses, handling enrollment, contribution processing, and the nondiscrimination testing that keeps a plan compliant with IRS rules. It's built to plug into payroll systems so contributions flow automatically each pay period.
Guideline pros:
- Automated compliance testing that most owners can't do themselves
- Auto-enrollment features that boost employee participation
- Straightforward integration with common payroll providers
Guideline cons:
- Investment options are limited to the plan's fund menu, not a full advisory relationship
- Doesn't address the owner's personal financial plan outside the retirement plan itself
Best for: business owners ready to offer employees a 401(k) without building the administration in-house.
TurboTax Business: best financial planning tool for filing a simple return
TurboTax Business walks sole proprietors, single-member LLCs, and simple partnerships through a guided interview to file federal and state business returns. It handles the filing itself well but stops there — it doesn't help you plan ahead for next year's tax bill.
TurboTax Business pros:
- Guided interview format reduces filing errors for straightforward returns
- Covers most common small business entity types
TurboTax Business cons:
- No forward-looking tax strategy — it files what already happened
- Gets harder to trust as entity structure or multi-state activity gets complicated
Best for: the simplest business structures with minimal complexity.
Spreadsheet templates: best budget financial planning option for early-stage businesses
A well-built spreadsheet can track income, expenses, and basic cash flow projections for a business with a handful of transactions a month. It costs nothing and gives you full control over categories, which appeals to owners who want to see every number themselves before paying for a tool.
Spreadsheet template pros:
- No subscription cost
- Full customization over categories and formulas
- Fine for very low transaction volume
Spreadsheet template cons:
- Entirely manual — errors compound as volume grows
- No compliance testing, no automated tax filing, no audit trail
Best for: pre-revenue or very early-stage businesses with minimal transaction volume.
“The advisor who only manages your portfolio and the accountant who only files your return are each working with half the story.”
How we compared these tools
This is a comparison of fit, not a ranking. The five comparison criteria are integration with other financial systems, whether an advisory relationship carries a fiduciary standard, compliance coverage, scalability as the business grows, and time saved versus manual work. A fee-only financial advisor reviews household planning in coordination with the owner's CPA and attorney; single-purpose tools like Gusto and Guideline address specific administrative needs. No overall score or category leader is assigned.
Which financial planning tool should you choose in 2026?
Choose based on the work you need done. A fee-only financial advisor can review how retirement contributions, a business sale, and investments fit your household plan, in coordination with your CPA and attorney. QuickBooks Online addresses bookkeeping, Gusto addresses payroll, and Guideline addresses retirement plan administration. An advisor does not replace those services or tax-return preparation; confirm advisory fees, service scope, and minimums with each firm.
Owners evaluating any advisor relationship should know what to look for in a fee-only fiduciary before signing on — the fee-only structure matters as much as the credentials.
Talk to an advisor about your business
See if an integrated planning relationship fits your business and assets.
FAQ
What is the best financial planning tool for small business owners in 2026?
The appropriate tool depends on the work you need done; this is a comparison of fit, not a ranking. A fee-only financial advisor can review household planning with your CPA and attorney, while QuickBooks Online addresses bookkeeping and Gusto addresses payroll.
Do small business owners need a financial advisor or just accounting software?
Accounting software tracks what already happened; a financial advisor plans what happens next with taxes, retirement, and investments. Owners with meaningful assets typically need both, not one instead of the other.
Is QuickBooks Online enough for tax planning?
No. QuickBooks Online tracks transactions and generates reports but doesn't provide tax strategy or retirement account guidance. It feeds accurate numbers to whoever does that planning.
When should a small business set up a 401(k)?
Most owners set one up once they have steady payroll and want to attract or retain employees with a retirement benefit. Providers like Guideline handle the administration and compliance testing once you're ready.
How much in investable assets do you need to work with a fee-only financial advisor?
Requirements vary by firm. Ask each advisor about asset minimums, advisory fees, and service scope before deciding whether the relationship fits your needs.
How does a fee-only fiduciary advisor differ from a commission-based one?
A fee-only fiduciary advisor is paid by clients, not by product commissions, and must act in the client's best interest. Commission-based compensation can create an incentive to recommend certain products; fee-only compensation reduces that conflict, but does not eliminate every potential conflict. Review each firm's disclosures and service scope.
Can spreadsheet templates replace financial planning software in 2026?
Only for very early-stage businesses with low transaction volume. Once revenue and complexity grow, manual entry becomes a liability compared to automated bookkeeping and compliance tools.
What's the difference between bookkeeping software and financial planning?
Bookkeeping software like QuickBooks Online records and categorizes transactions. Financial planning looks ahead — coordinating tax strategy, retirement contributions, investments, and estate planning as one picture.
One last thing
The tool most owners skip isn't a piece of software — it's estate planning. Business owners with significant assets often have retirement accounts and investment portfolios dialed in but no coordinated plan for what happens to the business itself. Worth a look at estate planning strategies built for high-net-worth families before assuming the rest of the plan covers it.
Related guides
- Best fiduciary financial advisor qualities to look for
- Best tax-efficient retirement accounts for high earners
About Vital Investment Management: a fee-only, SEC-registered investment adviser serving individuals, families and business owners in New England and Colorado. Vital does not prepare tax returns.