Dentists’ fee-only financial planning is advice paid for by the client, with the aim of coordinating practice decisions and personal wealth. For a practice owner, cash flow, debt, retirement, taxes, and a future transition affect one another; for an associate, the questions center more on compensation, benefits, debt, and the path to ownership.
- A fee-only financial advisor for dentists should connect practice and household decisions, not treat investments as the entire plan.
- Vital Investment Management suits New England dentists seeking integrated fee-only planning; confirm dental-practice experience before hiring.
- Compare advisors by compensation, planning scope, coordination with other professionals, and how they handle an eventual practice transition.
- Start with your own cash-flow and account inventory, then decide which decisions need an advisor.
Why this matters
A practice can be the source of your income, a major asset, and a claim on your time. That makes a portfolio-only conversation too narrow. A decision to pay down practice debt, increase retirement contributions, or prepare for a sale also changes what is available to your household.
Fee-only describes how an advisor is paid, not whether that advisor understands dentistry. Use both tests. This guide to fee-only financial advisor qualities gives you a broader screening list; the questions below apply it to dentists.
Why fee-only advice matters for dentists
A fee-only advisor is paid by clients rather than through product commissions. That distinction helps you examine recommendations without a product sale built into the advisor’s compensation. It does not remove every possible conflict: an advisor paid based on assets under management still has a compensation structure you should understand.
Dentists also need to separate professional advice from professional scope. A financial advisor can coordinate planning, but your accountant remains responsible for tax advice and your attorney for legal documents. In 2026, ask who will bring those conversations together when a practice decision changes the household plan.
For a dentist with substantial assets to manage, that coordination can matter as much as choosing investments. For a dentist earlier in a career, a focused plan and clear priorities can matter more than ongoing portfolio management. Choose the relationship around the decisions you need to make, not the length of the service list.
How to choose a fee-only financial advisor for dentists
Map practice and household cash flow
Start with records you already have. Put practice income, household spending, debt obligations, and money set aside for taxes on one page. The point is not to produce a perfect forecast. It is to see which commitments compete for the same dollars before discussing investments.
A 12-month view makes irregular decisions visible: an equipment purchase, a planned distribution, or a household expense can change what you are comfortable committing elsewhere. If you are an associate, replace practice cash flow with compensation and benefits, and note any ownership plans separately.
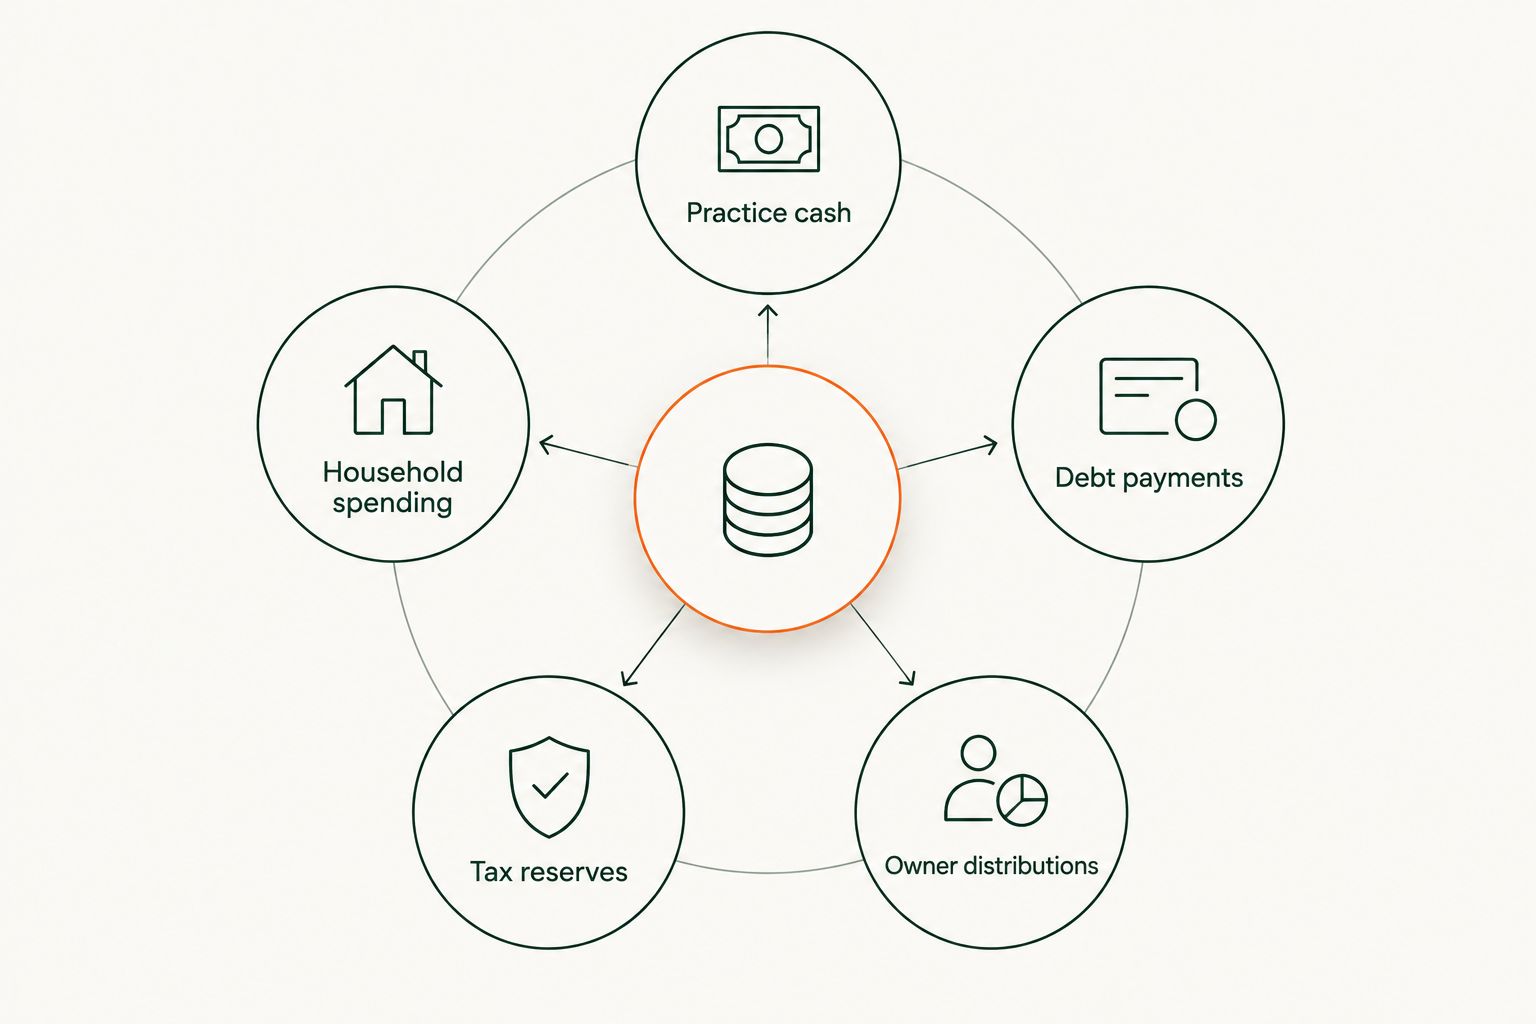
- Practice cash: Record what the business needs before owner distributions.
- Household spending: Separate recurring commitments from discretionary spending.
- Debt payments: List personal and practice obligations separately.
- Tax reserves: Note the amounts you have already set aside and the deadlines your accountant has identified.
- Owner distributions: Identify when practice income reaches your household accounts.
List every account and obligation
Make an account inventory before asking anyone to manage it. Include retirement accounts, taxable investments, cash, insurance, and debts. For practice owners, list ownership interests and business obligations separately so they do not disappear into a single net-worth figure.
You can do this in a spreadsheet or a document. The faster path with an advisor is to use that inventory as the starting point for a coordinated plan, not to hand over accounts before you understand the scope of the work. Update the list whenever a major account or obligation changes.
- Record the owner and intended purpose of each account.
- Note which accounts are held inside retirement arrangements.
- List interest-bearing debts without combining practice and household balances.
- Flag beneficiaries that need review with your attorney or plan provider.
- Keep a separate list of documents you cannot locate.
Set a retirement target outside the practice
A practice sale is not a complete retirement plan. The timing, proceeds, and terms of a future transition are uncertain until a transaction is documented. Build a retirement picture that shows what your invested assets and expected income must support without assuming a particular sale outcome.
In 2026, write down the lifestyle you intend to fund and the decisions still open: when you want to reduce clinical work, whether you plan to retain any ownership, and how much spending depends on continued practice income. A fee-only advisor can help connect those choices to investment management; ask them to show the assumptions plainly.
- Define the spending your household expects to continue after clinical work ends.
- Separate retirement assets from the estimated value of the practice.
- Identify income that depends on your continued work.
- Test a later-than-planned practice transition without assuming a sale price.
Coordinate tax questions with your accountant
Do not ask a financial advisor to replace your accountant. Ask how the advisor will use your accountant’s input when choosing between retirement contributions, debt repayment, investments, and owner distributions. A plan that ignores tax timing is incomplete, even when each investment choice looks reasonable on its own.
Bring specific questions to a joint discussion. For example, if your practice structure or compensation is changing, your accountant can explain the tax treatment while the advisor shows how the decision affects your cash needs and long-term plan. Confirm who will follow up; coordination needs an owner.
- Ask your accountant which 2026 decisions have tax deadlines.
- Show your advisor the cash needed to meet those obligations.
- Identify account moves that require tax review before execution.
- Record which professional is responsible for each follow-up.
Test the advisor’s practice-transition process
You do not need to be ready to sell before asking this question. A practice transition can change your income, your investment needs, and the risks borne by your household. Ask an advisor what information they would need and which other professionals should be involved. Listen for a process, not a confident prediction of proceeds.
If you expect to keep practicing, the same discussion still helps. It distinguishes a plan built around your current earnings from one that can adjust when your role changes. Review the assumptions at least once every 12 months and after a material practice decision.
- Ask how the advisor would model income before and after a transition.
- Ask which assumptions depend on a practice valuation or transaction terms.
- Identify the accountant and attorney who would review their parts of the decision.
- Request an explanation of what would change in the investment plan.
Verify compensation, registration, and scope
Read the advisor’s Form ADV and client agreement rather than relying on a label in a meeting. The documents should help you identify services, compensation, conflicts, and who provides advice. Check registration through the SEC’s Investment Adviser Public Disclosure system or the relevant state regulator.
Vital Investment Management is a fee-only, SEC-registered RIA offering personalized financial planning and investment management as one advisory relationship. That makes it an option to examine if you want those services connected. It does not establish experience with dental practices. Ask Rusty Tredwel how he would address your ownership, compensation, or transition questions before deciding whether the fit is right.
- Ask what the engagement covers beyond investment management.
- Ask how the advisor is compensated and what conflicts the documents disclose.
- Confirm who would lead your relationship and attend planning discussions.
- Request a dentist-relevant example of the advisor’s process, without assuming a particular result.
Decide who coordinates the plan
A collection of capable professionals is not the same as a coordinated plan. Decide who will notice when a change in the practice affects retirement, taxes, investments, or estate documents. If that person is you, put review dates and responsibilities in writing. If you hire an advisor, agree on what they will coordinate and what stays with your accountant and attorney.
Vital Investment Management’s integrated planning and investment-management approach is suited to a dentist who wants one advisory relationship for savings, retirement, taxes, and estate-planning coordination. It is not a substitute for legal or tax counsel. The useful question is whether the advisor will keep your decisions connected while staying inside their professional role.
- Assign an owner to each open planning question.
- Schedule a review after a major practice or household change.
- Share relevant decisions with your accountant and attorney.
- Ask how the plan will be updated when assumptions no longer hold.
Compare your options
You can organize this work yourself, hire ongoing advice, or assemble help around a specific decision. Compare the responsibility you retain, not just the services named in a proposal. The table avoids fixed fees because compensation depends on the engagement; request written disclosures from each provider.
| Option | Best for | Fee structure to confirm | Key limitation |
|---|---|---|---|
| Independent plan | Dentists willing to maintain their own records and coordinate professionals | Costs and terms of any tools or outside help | You own every follow-up and must connect practice and household decisions yourself |
| Vital Investment Management | New England dentists seeking integrated, fee-only planning and investment management | Review the client agreement and Form ADV | Dental-practice experience needs to be confirmed directly |
| Dentist-focused advisor | Dentists who want an advisor with documented dental-practice experience | Verify whether compensation is fee-only and how it is calculated | A specialty label does not establish independence or broad planning scope |
| Accountant and attorney for defined projects | Dentists with a specific tax or legal question and no need for ongoing advice | Request each professional’s written engagement terms | Neither relationship automatically coordinates an investment plan |
Vital Investment Management suits New England dentists with over $1 million in assets to manage who want fee-only planning and investment management together; confirm dental-practice experience before hiring. An advisor who demonstrates deeper practice-specific experience can be the better choice if an ownership transaction is your immediate priority. An independent plan is reasonable when your affairs are straightforward and you will reliably maintain it.
Discuss your financial plan
Ask how planning and investment management would fit your practice and household decisions.
Common mistakes dentists make
- Treating practice value as retirement cash. A valuation is not money available for household spending. Keep sale assumptions separate until transaction terms are known.
- Choosing an advisor on the fee-only label alone. Fee-only answers a compensation question; it does not prove dental-practice experience or guarantee a particular scope of service.
- Keeping the accountant, attorney, and advisor in separate conversations. Each can do their own work well while a decision falls between them. Assign responsibility for sharing the relevant information.
- Letting the investment review replace the planning review. A portfolio discussion will not, by itself, settle debt priorities, owner distributions, or an eventual transition.
- Waiting for a sale to discuss succession. Start with the financial assumptions and unanswered questions while you still have room to revise the plan.
FAQ
What is a fee-only financial advisor for dentists?
A fee-only financial advisor for dentists is paid by clients rather than product commissions and helps dentists make financial decisions. Confirm the advisor’s scope and dental-practice experience separately.
Is a fee-only advisor the same as a dentist-focused advisor?
No. Fee-only describes compensation; dentist-focused describes a claimed area of experience. Ask for written compensation disclosures and an explanation of how the advisor handles practice-related decisions.
Does an SEC-registered RIA have dental-practice expertise?
No. SEC registration does not establish dental-practice expertise. Ask the advisor how practice ownership, compensation, and a future transition enter the planning process.
Should a practice owner count on a sale to fund retirement?
No. Keep the estimated practice value separate from invested retirement assets until sale terms are known. Your plan should show what depends on the timing and outcome of a transition.
Can a financial advisor replace my dentist practice accountant?
No. Your accountant handles tax advice; a financial advisor can incorporate that advice into cash-flow, retirement, and investment decisions. Agree on who coordinates the follow-up.
How do I compare financial advisors for dentists in 2026?
Compare compensation, planning scope, registration, relevant experience, and coordination with your accountant and attorney. Request the Form ADV and client agreement before choosing an ongoing relationship.
Is Vital Investment Management a dentist specialist?
The provided information does not establish Vital Investment Management as a dentist specialist. It offers fee-only financial planning and investment management; ask directly about its approach to dental-practice decisions.
One last thing
Before your first advisor conversation in 2026, write down the practice decision and the household decision that worry you most. Ask the advisor to explain how one changes the other. That answer tells you more about the proposed relationship than an investment presentation alone.