Retirement planning for university professors is the coordination of university benefits, investments, taxes, and healthcare to replace employment income after academic work ends. Your plan needs to account for faculty retirement arrangements, accounts from previous institutions, and any teaching or consulting you intend to continue.
- Retirement planning for university professors starts with written benefit rules, not a rollover or pension election.
- Coordinate university retirement benefits, Social Security, healthcare, and investment withdrawals before choosing your retirement date.
- VIMNewEngland fits New England professors seeking integrated, fee-only financial planning and investment management.
- Compare phased retirement with full retirement using household spending, benefit eligibility, and after-tax income.
Why retirement planning matters for university professors
Leaving a university changes more than your paycheck. Pension elections, medical coverage, continued faculty appointments, and account distribution rules can each follow different schedules. A retirement date that works professionally still needs to work financially.
For a professor with substantial investments, the central question is coordination: which income source pays household expenses, which assets remain invested, and which decisions cannot easily be reversed? Start with the documents governing your benefits rather than assumptions based on a colleague's experience.
VIMNewEngland is best for New England professors seeking integrated, fee-only retirement planning and investment management. Its advisory relationship covers savings, retirement, taxes, and estate planning. That approach suits households seeking ongoing coordination; it is a broader engagement than someone seeking only help with a university benefits form needs.
Build your university retirement plan
1. Inventory your accounts and benefit rules
Build a spreadsheet before moving money. List each retirement account, its tax treatment, investment holdings, beneficiaries, and the institution responsible for answering benefit questions. Include accounts left behind after earlier faculty appointments.
University benefits are not interchangeable. A 403(b), a governmental 457(b), a nongovernmental 457(b), and a pension have different rules. In particular, a nongovernmental deferred-compensation plan does not have the same rollover treatment or creditor protections as a governmental plan. Confirm the plan type in writing.
Separate account balances from promised income. A pension estimate is not an investment account you can freely withdraw, and an annuity contract can have distribution restrictions that differ from the university plan's general rules. Ask the administrator which rules apply to each holding.
For your 2026 review, use current statements and current plan documents. Old enrollment materials are not a substitute for the rules governing an election today.
- Record every account's owner, tax status, and beneficiary.
- Request current pension estimates and distribution documents.
- Identify vesting requirements, contract restrictions, and election deadlines.
- Ask whether retiree benefits depend on service or appointment status.
2. Map your household spending and income
Start with what retirement needs to fund, not a percentage of your final salary. Separate essential expenses from travel, family support, charitable giving, and other flexible spending. Include taxes and healthcare rather than treating them as afterthoughts.
Then map dependable income against those expenses. Pension payments, Social Security, a spouse's earnings, and portfolio withdrawals serve different roles. Consulting and adjunct work belong in a separate category until you have a dependable commitment; do not make essential spending depend on work you have not secured.
Build both a full-retirement scenario and a reduced-work scenario. A phased arrangement can change your salary, university contributions, medical eligibility, and pension timing. Obtain the actual terms before treating it as a bridge.
You can build this comparison with a spreadsheet and benefits statements. VIMNewEngland's retirement planning and investment management provide an integrated advisory path when you want household cash flow, taxes, and investments considered together rather than managed as separate projects.
- Establish essential spending and flexible spending totals.
- Separate confirmed income from proposed teaching or consulting income.
- Compare full retirement with the university's written phased-retirement terms.
- Include your spouse's benefits and retirement timetable.
3. Compare pension and account distribution choices
Request every available pension payment option and compare what happens after either spouse dies. A larger initial payment is not automatically the better household choice. Survivor coverage matters when a spouse depends on that income.
Review annuity contracts separately from other investments. Determine whether withdrawals, transfers, or income elections have restrictions, and whether an election is reversible. Do not assume all holdings inside the same university account move under identical rules.
Do not roll over a university account until you understand what you would give up. Compare investment choices, expenses, distribution access, creditor protections, and any applicable guarantees. Keeping assets in a former employer's plan is a legitimate option, not an administrative failure.
The IRS generally applies an additional tax to retirement-plan withdrawals before age 59½, with exceptions depending on the account and circumstances. Governmental 457(b) distributions generally follow different early-distribution rules. Verify the applicable exception before relying on an account for an early-retirement bridge.
- Compare pension income with and without survivor protection.
- Request contract-specific withdrawal and transfer rules.
- Review rollover trade-offs before authorizing a transfer.
- Confirm early-distribution treatment with your tax professional.
4. Coordinate taxes with your withdrawal plan
Create a household withdrawal map that distinguishes taxable investments, tax-deferred accounts, and Roth accounts. The order of withdrawals affects taxable income; it should follow your circumstances rather than a universal rule about which account to spend first.
A lower-income period between university employment and later retirement income deserves a separate tax projection. Compare ordinary withdrawals and possible Roth conversions with your expected tax position. A conversion creates taxable income and should not be treated as automatically beneficial.
For 2026 decisions, examine federal and state taxes together. A New England professor retiring in another state needs to review the rules in the destination state rather than carrying over assumptions from a working-year tax return. Include pension treatment and investment income in that review.
VIMNewEngland includes tax planning within its financial planning and investment management relationship. Your tax preparer remains part of the process: proposed transactions should be checked against the return they will affect. The tax-planning guide for high-net-worth retirees covers the broader retirement context.
- Identify each account's tax treatment and available withdrawal rules.
- Project pension, earnings, investment income, and proposed withdrawals together.
- Compare Roth conversion scenarios before moving assets.
- Review relocation plans with a qualified tax professional.
5. Align Social Security and healthcare dates
Treat your last teaching day, pension start date, Social Security claim, and healthcare transition as separate decisions. They do not need to occur together, but the gaps between them need funding and coverage.
For a 2026 claiming decision, Social Security Administration guidance establishes that delayed retirement credits stop at age 70. Waiting beyond that age does not increase your retirement benefit through additional delayed credits. Compare claiming dates using your earnings record, household cash needs, and survivor considerations.
Medicare eligibility generally begins at age 65. Medicare's enrollment guidance distinguishes coverage based on current employment from retiree coverage and COBRA; do not assume that any university-sponsored coverage allows you to postpone enrollment without consequences. Confirm how your specific coverage coordinates with Medicare.
If you retire before Medicare eligibility, obtain the actual coverage terms for the intervening period. A spouse's plan, a university retiree arrangement, and individual coverage require separate eligibility checks. Coverage is not established by putting an estimated expense into a spreadsheet.
- Obtain personalized Social Security benefit estimates.
- Compare household income under different claiming dates.
- Ask the benefits office how coverage changes after employment ends.
- Confirm Medicare enrollment requirements for your specific situation.
6. Organize investments around retirement needs
Review the household portfolio as one portfolio, even when assets sit at several providers. Multiple university accounts can hold overlapping investments. Diversification depends on the underlying holdings, not the number of statements arriving in your inbox.
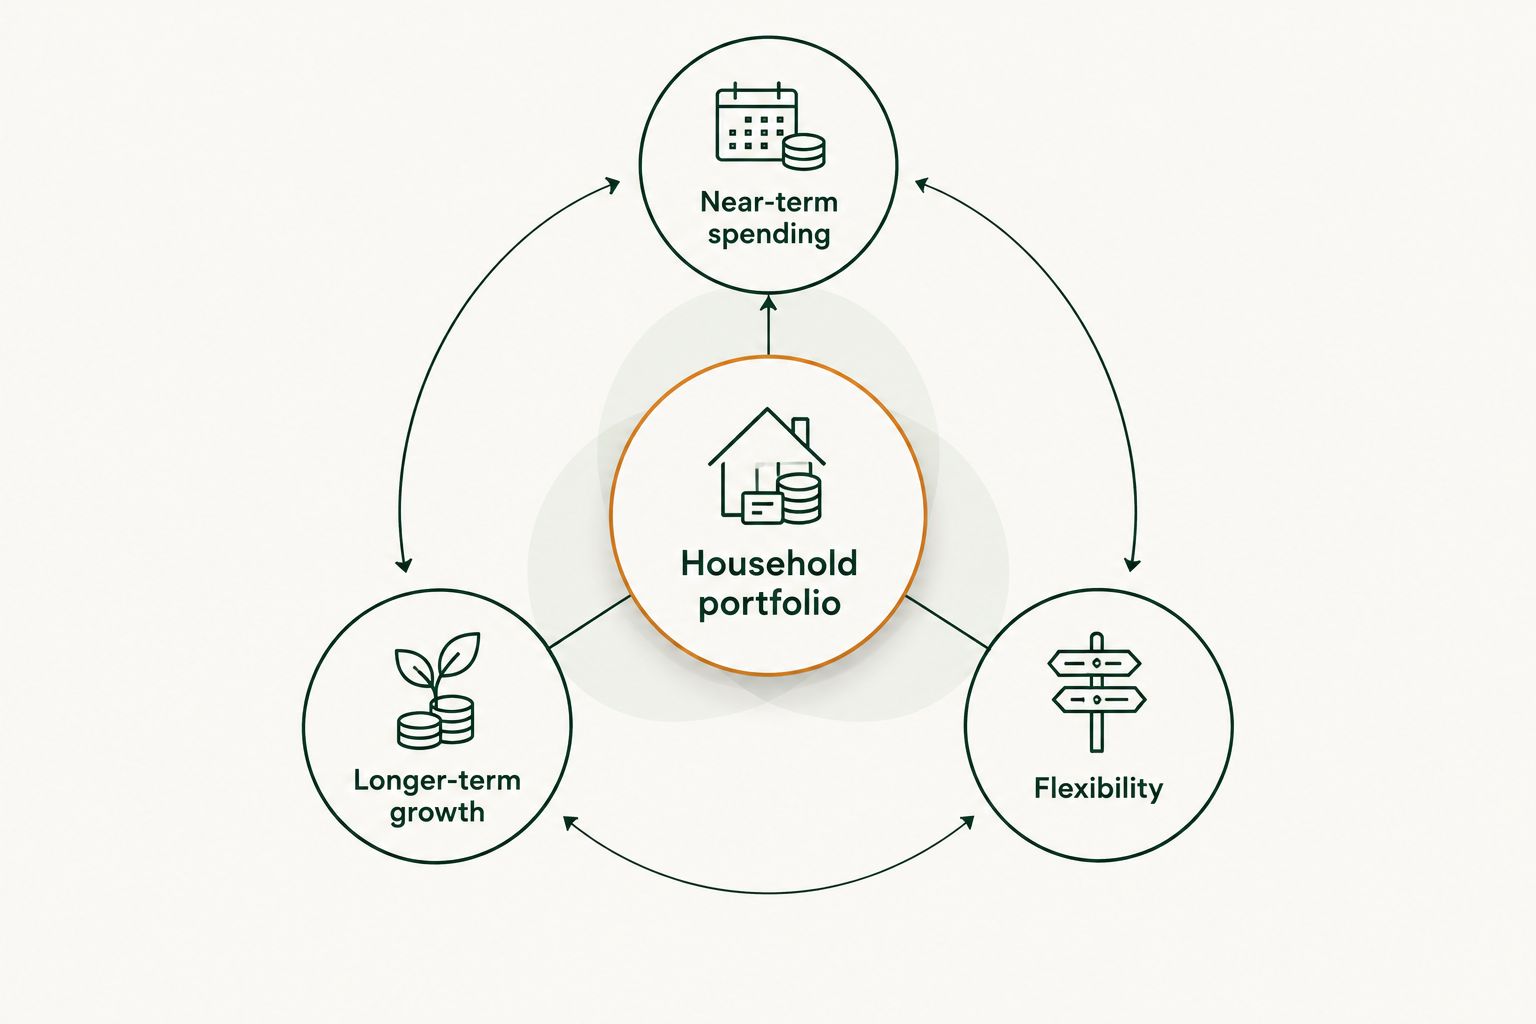
Assign the portfolio clear jobs: near-term spending, longer-term growth, and flexibility for unexpected needs. Then decide which accounts fund each job. Keep the allocation consistent with your spending needs and ability to tolerate losses; a retirement date alone does not determine the right investment mix.
For New England professors with more than $1,000,000 in assets to manage, VIMNewEngland seeks an ongoing financial planning and investment management relationship. Discuss the service scope and responsibilities before deciding whether ongoing management matches your needs. Integrated advice does not eliminate market risk or replace legal and tax specialists.
Document a withdrawal process before market stress arrives. Specify how spending is funded, when investments are reviewed, and what changes would trigger a revised plan.
- Review holdings across every household investment account.
- Identify overlap and concentrated positions.
- Assign assets to near-term spending and longer-term needs.
- Write down withdrawal and portfolio-review responsibilities.
7. Update beneficiaries and assign responsibilities
Retirement is a useful point to reconcile account beneficiaries with your estate documents. Beneficiary designations generally govern retirement-account transfers, so a will alone does not resolve every inheritance question. Ask your attorney to review how the documents and accounts work together.
Include a spouse or trusted person in the practical plan. They should know where records are stored, which professionals to contact, and how household expenses are paid. Access arrangements should respect account rules and privacy rather than rely on shared passwords.
Create a 2026 retirement decision calendar with university deadlines, coverage transitions, and planned tax reviews. Assign each task to a person: you, the benefits administrator, the advisor, the accountant, or the attorney. Responsibility is clearer when it is written down.
- Review primary and contingent beneficiaries.
- Reconcile account designations with estate documents.
- Organize statements, contacts, and benefit-election records.
- Assign an owner and deadline to every unresolved decision.
Compare retirement planning options
Choose the option that matches the decisions you need help making. University benefits support and personal financial advice serve different purposes; neither automatically replaces the other.
| Option | Best for | What it helps you do | Key limitation |
|---|---|---|---|
| Spreadsheet and plan documents | Professors comfortable managing their own plan | Organize accounts, spending, and deadlines | You remain responsible for interpretation and coordination |
| University benefits office | Professors clarifying employer benefits | Explain university rules and benefit elections | Its role concerns employer benefits, not your entire household plan |
| Tax professional | Professors evaluating taxable transactions | Review tax consequences and return implications | Tax advice alone does not coordinate investment management or university benefits |
| VIMNewEngland | New England professors seeking ongoing integrated advice | Connect retirement, investments, taxes, and estate planning | An ongoing advisory relationship is broader than a single benefits question |
Before engaging an advisor, ask who handles implementation and how university-specific questions are resolved. Fee-only compensation describes how an advisor is paid; it does not remove the need to review conflicts, qualifications, and service scope. SEC registration is not a performance guarantee or government endorsement.
Common mistakes university professors make
- Copying a colleague's retirement election. Similar faculty titles do not establish identical plan rules, household needs, or survivor requirements. Compare your own documents.
- Treating phased retirement as continued full benefits. Reduced work and benefit eligibility are separate questions. Request written confirmation before choosing the arrangement.
- Moving every account immediately. A rollover can change distribution access or remove contract features. Complete the comparison before signing transfer instructions.
- Counting tentative academic work as essential income. A proposed course or consulting engagement is not committed income. Build a plan that covers essentials without it.
- Ignoring the surviving spouse's position. Model income and account access after either spouse dies, not just while both are living.
FAQ
What's the first step in retirement planning for university professors?
Inventory your retirement accounts and obtain the written rules for your university benefits. Identify pension choices, distribution restrictions, and healthcare eligibility before selecting a retirement date.
Should a university professor roll a 403(b) into an IRA?
A rollover should follow a comparison, not happen automatically at retirement. Review investment choices, expenses, distribution access, creditor protections, and any contract features you would lose.
Is a university 457(b) the same as a 403(b)?
No, a 457(b) and a 403(b) have different rules. Also distinguish a governmental 457(b) from a nongovernmental 457(b), because rollover treatment and creditor protections differ.
Can I retire from a university before Medicare eligibility?
Retiring before Medicare eligibility requires a separate healthcare coverage plan. Confirm eligibility and coverage terms through your university, a spouse's employer, or an individual plan before employment ends.
Should professors claim Social Security when they stop teaching?
Stopping teaching does not require you to claim Social Security immediately. Compare claiming dates with household income needs, your earnings record, and survivor benefits; delayed retirement credits stop at age 70.
Does phased retirement preserve all university benefits?
Phased retirement does not automatically preserve every benefit. Ask the university to confirm medical coverage, retirement contributions, pension treatment, and appointment conditions in writing.
Who can help coordinate university retirement benefits and investments?
A financial advisor can coordinate the household plan, while the university benefits office confirms employer rules. Keep your tax professional and estate attorney involved for decisions within their respective specialties.
One last thing
An election deadline can arrive before you feel ready to retire. Put irreversible decisions at the top of your 2026 checklist, not at the bottom beneath account consolidation. Start with pension elections, annuity terms, and coverage transitions; organize investments after those constraints are clear.