Best overall: fiduciary accountability. Best for replacing a paycheck: retirement-income planning. Best for complex households: tax coordination. This guide ranks the best financial advisor qualities for Colorado retirees in 2026 and explains how to evaluate an integrated advisory relationship such as VIMNewEngland.
- The best financial advisor qualities for Colorado retirees start with documented fiduciary accountability and clear compensation disclosures.
- Choose retirement planning that connects withdrawals, investments, taxes, and estate decisions rather than treating them separately.
- VIMNewEngland suits retirees seeking financial planning and investment management within one advisory relationship.
- Ask each advisor to explain the trade-offs, implementation responsibilities, and review process before signing.
Why this matters
Retirement changes the job your money must do. Your portfolio now supports spending, while withdrawals interact with taxes, healthcare expenses, investment risk, and what you intend to leave your family.
A Colorado address alone does not establish retirement-planning competence. Look for an advisor who understands your household, identifies decisions requiring Colorado-specific tax or legal review, and explains who handles each part of the work.
For your 2026 search, evaluate the advice process before the investment presentation. A polished portfolio proposal does not explain how you will fund an unexpected expense or support a surviving spouse.
What makes the best financial advisor for Colorado retirees?
Use these criteria before comparing personalities or credentials:
- Accountability: The advisor explains fiduciary obligations, compensation, conflicts, and the scope of the engagement in writing.
- Income practicality: The plan connects spending needs with withdrawals, benefits, cash reserves, and investment decisions.
- Tax awareness: Recommendations consider tax consequences and identify matters requiring your tax professional.
- Investment discipline: Portfolio decisions follow your needs and risk capacity rather than predictions about the next market move.
- Family coordination: Account ownership, beneficiaries, and estate documents receive attention alongside investments.
- Communication: You understand the recommendation, its disadvantages, and who is responsible for implementation.
The strongest advisor explains how a recommendation affects the rest of your financial life—not just the account being discussed.
Financial advisor qualities at a glance
These are ranked qualities, not a ranking of advisory firms. Each addresses a different retirement need; a suitable advisor should demonstrate all of them.
| Rank and quality | Best for | Standout evidence | Key limitation |
|---|---|---|---|
| 1. Fiduciary accountability | Evaluating trust and conflicts | Written explanation of duties and compensation | Does not guarantee results or remove conflicts |
| 2. Retirement-income planning | Replacing employment income | A withdrawal plan connected to household spending | Assumptions need regular review |
| 3. Tax coordination | Managing interacting tax decisions | Recommendations reviewed alongside the tax picture | Does not automatically include tax preparation |
| 4. Investment discipline | Maintaining a suitable portfolio | Written reasoning for allocation and rebalancing | Cannot prevent market losses |
| 5. Estate coordination | Protecting family intentions | Beneficiary and ownership review with legal coordination | Does not replace an estate attorney |
| 6. Clear communication | Sharing decisions and maintaining continuity | Plain-language explanations and assigned responsibilities | A pleasant relationship is not proof of competence |
1. Fiduciary accountability: best for evaluating trust
Fiduciary accountability means understanding the duty your advisor owes you and the relationship in which that duty applies. Ask for the explanation in writing, together with compensation arrangements, material conflicts, and the services covered by your agreement.
Fee-only compensation and fiduciary obligations answer different questions. One concerns how an advisor is paid; the other concerns the standards governing advice. Neither phrase eliminates the need to read disclosures.
Fiduciary accountability pros:
- Establishes a clear basis for evaluating recommendations.
- Makes compensation and conflicts part of the conversation.
- Helps distinguish advisory responsibilities from assumptions.
Fiduciary accountability cons:
- Does not guarantee investment performance.
- Disclosures still require your attention and questions.
Best for: Retirees comparing relationships with different compensation models or service scopes.
Ask: “What conflicts remain in this relationship, and how do you address them?” An answer that acknowledges conflicts is more informative than a claim that none exist. SEC registration is not an endorsement of an advisor's skill.
Verdict: Buy advice only after the advisor's obligations and conflicts are clear.
2. Retirement-income planning: best for replacing a paycheck
Retirement-income planning turns assets and benefits into a household spending plan. A suitable advisor explains where withdrawals will come from, how investment sales support them, and what changes when expenses rise or markets decline.
Bring 12 months of spending records to distinguish recurring expenses from irregular purchases. That is a preparation step, not a claim that last year's spending predicts the rest of retirement.
Retirement-income planning pros:
- Connects investment decisions to actual household needs.
- Separates routine expenses from larger planned withdrawals.
- Makes spending adjustments easier to discuss before a disruption.
Retirement-income planning cons:
- Depends on assumptions that will change.
- Requires you to provide realistic spending information.
Best for: New retirees and households deciding how investments will supplement Social Security or pension income.
Ask an advisor to discuss 3 scenarios: ordinary spending, a market decline, and a major unplanned expense. The point is not to predict which occurs. It is to understand which decisions change in each situation.
Verdict: Buy a retirement-income process, not just an investment allocation.
3. Tax coordination: best for complex household decisions
Tax-aware advice considers how a recommendation affects your broader tax position. Retirement withdrawals, investment sales, charitable gifts, and Roth conversion decisions should not be evaluated independently when their effects interact.
For Colorado retirees in 2026, ask how the advisor incorporates current federal and Colorado rules. If you maintain ties to New England or another state, identify residency questions for your tax professional rather than assuming an investment advisor resolves them.
Tax coordination pros:
- Brings tax consequences into decisions before implementation.
- Helps your advisor and tax professional work from shared assumptions.
- Makes competing objectives visible, including spending and legacy goals.
Tax coordination cons:
- Does not automatically include preparing or filing returns.
- A tax-saving strategy can introduce other costs or restrictions.
Best for: Retirees with multiple account types, investment gains, business interests, or multistate considerations.
Ask: “Who reviews the tax assumptions before this transaction happens?” Clarify whether the advisor communicates with your tax professional and what authorization that requires. Do not mistake tax-aware investment management for a tax-preparation engagement.
Verdict: Hold any tax-driven transaction until its assumptions and review responsibilities are clear.
4. Investment discipline: best for staying aligned with your plan
Investment discipline connects your portfolio to your spending needs, time horizon, and capacity for loss. It also establishes how the advisor responds when markets change without requiring a new prediction at every meeting.
Ask why the proposed investments belong in your retirement plan. The answer should address diversification, liquidity, expenses, and risk—not rely on recent returns or a confident economic forecast.
Investment discipline pros:
- Gives portfolio changes a consistent rationale.
- Connects investment risk with withdrawal needs.
- Creates a basis for reviewing concentrated holdings and liquidity.
Investment discipline cons:
- Diversification does not eliminate market risk.
- Following a plan can feel uncomfortable during market declines.
Best for: Retirees who want a repeatable decision process rather than frequent reactions to headlines.
In your 2026 interviews, ask what would justify changing the allocation and what would not. Also ask how the advisor evaluates assets outside the accounts under management. A portfolio recommendation needs context even when the advisor does not manage every holding.
Verdict: Skip recommendations built primarily around forecasts or recent winners.
5. Estate coordination: best for protecting family intentions
Estate coordination connects your financial accounts with your legal documents and intended beneficiaries. An advisor can help organize the financial picture and identify questions for an attorney, but that role does not replace legal advice.
Ask how account ownership and beneficiary designations will be reviewed against your intentions. Families with trusts, blended relationships, business interests, or property in multiple states should establish who evaluates the legal questions.
Estate coordination pros:
- Brings family intentions into investment and withdrawal discussions.
- Helps identify inconsistencies requiring professional review.
- Clarifies the handoff between advisor and attorney.
Estate coordination cons:
- Requires separate legal work when documents need drafting or revision.
- Depends on accurate information about accounts and family circumstances.
Best for: Retirees whose financial decisions must support a spouse, heirs, charitable beneficiaries, or a trust.
The limits of online estate planning become relevant when completing documents leaves unresolved questions about ownership, beneficiaries, or state-specific legal requirements. Ask who will resolve those questions rather than treating document completion as the end of the process.
Verdict: Buy coordinated planning; skip any suggestion that an investment review replaces legal review.
6. Clear communication: best for shared decisions and continuity
Clear communication means you can explain the recommendation after the meeting ends. Your advisor should describe the purpose, disadvantages, alternatives, and next action without requiring you to learn investment jargon.
If you share financial decisions with a spouse or partner, ask how both people participate. The relationship should not depend on one household member translating every recommendation for the other.
Clear communication pros:
- Helps you evaluate trade-offs before agreeing to a change.
- Makes implementation responsibilities easier to track.
- Supports continuity when household circumstances change.
Clear communication cons:
- Good rapport does not establish technical competence.
- Frequent meetings do not guarantee meaningful planning work.
Best for: Couples, surviving spouses, and retirees who want an understandable advisory relationship.
Ask who your regular contact will be, how questions between meetings are handled, and how unresolved tasks are recorded. Request an explanation of a recommendation you do not understand. The response tells you more than a promise of personalized attention.
Verdict: Wait if you still cannot explain the recommendation or your next step.
How these qualities were ranked
Accountability comes first because it establishes the terms of the relationship. Income planning follows because retirement assets must support spending. Tax coordination, investment discipline, estate coordination, and communication then determine how well the decisions fit together.
This is a decision framework, not a performance comparison or a claim that every retiree needs identical services. Assess each quality through written disclosures, specific explanations, and the proposed agreement—not the advisor's description alone.
Which financial advisor should you choose?
Choose the advisor who can connect retirement income, tax coordination, investment discipline, and estate coordination in one retirement plan. If the presentation stays focused on portfolio performance, ask for the missing connections before proceeding.
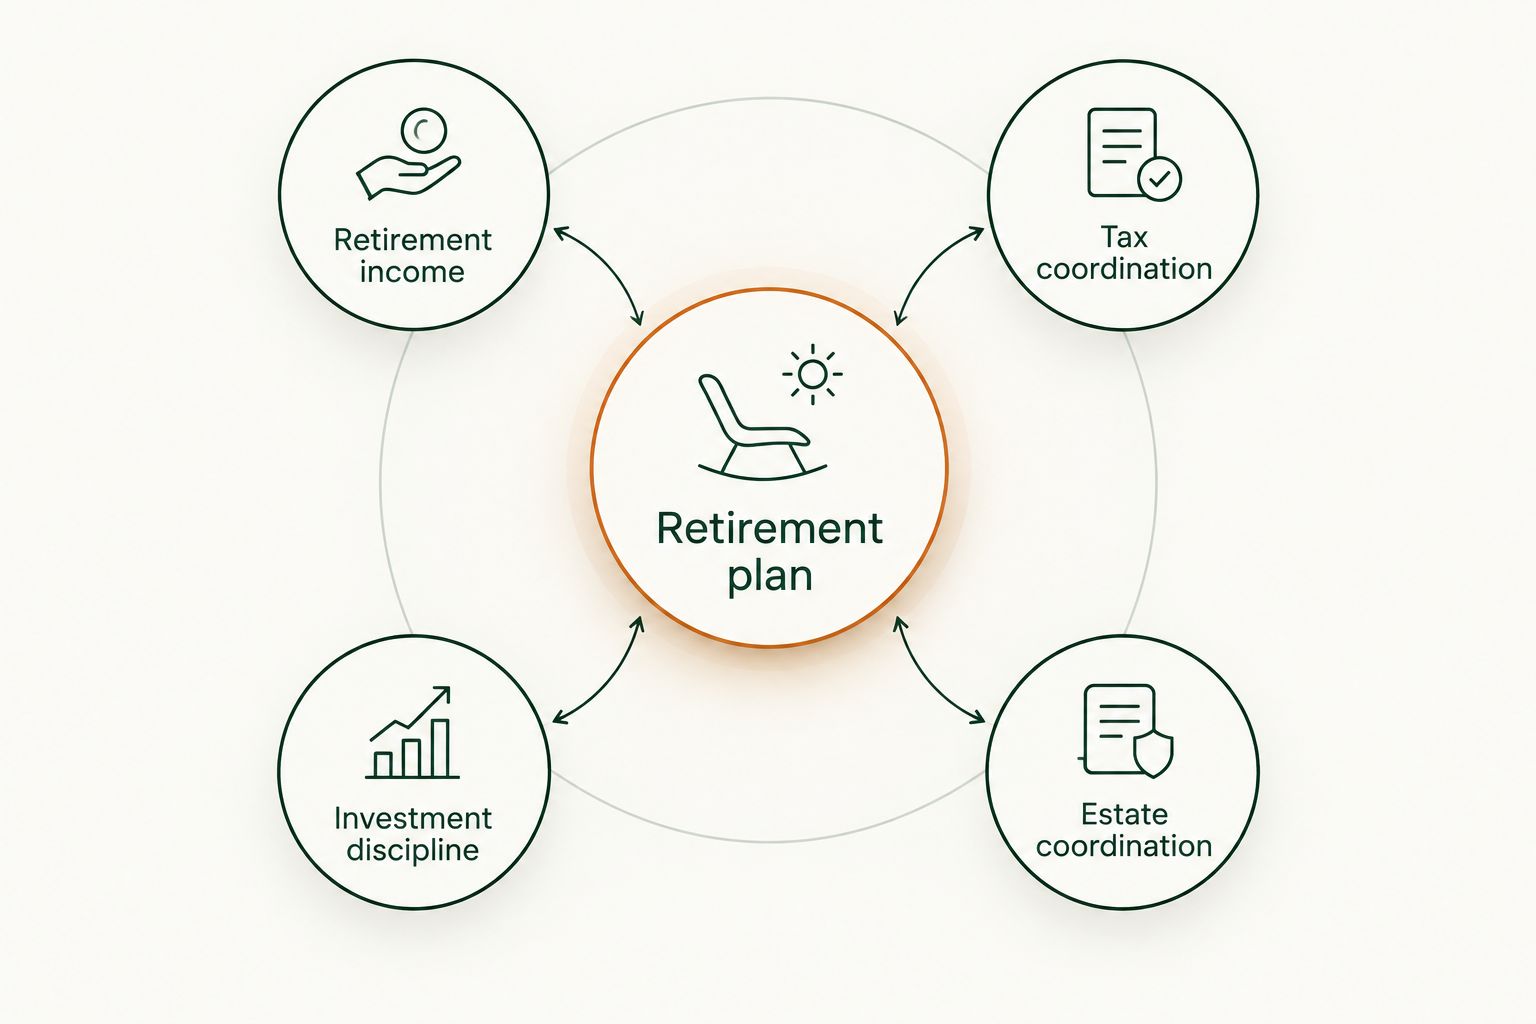
VIMNewEngland is a fit for retirees seeking financial planning and investment management in one advisory relationship. Its stated scope covers savings, retirement, taxes, and estate planning; review the services against the work you need rather than assuming every professional task is included.
VIMNewEngland is a fee-only, SEC-registered RIA. Those facts establish its stated business model and registration, not a guarantee of results or a substitute for evaluating fit.
For your 2026 decision, leave the meeting able to answer: What work is included? Who performs it? What requires another professional? What happens next? If those answers remain unclear, postpone the commitment.
FAQ
What are the best financial advisor qualities for Colorado retirees?
The best financial advisor qualities for Colorado retirees are fiduciary accountability, retirement-income planning, tax coordination, investment discipline, estate coordination, and clear communication. Evaluate each through written terms and specific explanations rather than labels alone.
Is a fee-only advisor automatically the right choice for retirement?
No. Fee-only describes compensation, not whether the advisor's expertise and service scope match your retirement needs. Review fiduciary obligations, conflicts, responsibilities, and the proposed work separately.
Does my retirement advisor need to live in Colorado?
A Colorado address does not establish retirement-planning competence. Ask how the advisor handles Colorado-specific questions, coordinates with local tax and legal professionals, and supports your preferred meeting arrangements.
Can a financial advisor prepare my estate documents?
Do not assume estate coordination includes preparing legal documents. Ask which tasks the advisor handles and which require an estate attorney, including drafting or revising documents.
What should I bring to a retirement advisor interview?
Bring account statements, spending records, benefit information, and a list of your main decisions. Describe relevant tax and estate documents, then ask how sensitive information should be shared securely.
Is SEC registration a guarantee that an advisor is good?
No. SEC registration is not an endorsement of skill or a guarantee of investment results. You still need to evaluate disclosures, qualifications, service scope, and fit.
What should I ask VIMNewEngland before becoming a client?
Ask VIMNewEngland how its integrated planning and investment management would address your retirement decisions. Confirm the advisor responsible for your relationship, the work included, compensation, and coordination with your tax and legal professionals.
One last thing
Ask an advisor to explain a recommendation they would advise against for your household—and why. The answer reveals whether the conversation includes limits and trade-offs, not just services to purchase.
Your 2026 retirement plan should make decisions clearer. Before signing, ask for the first priorities and who will carry each one through.