Best overall: coordinated retirement and investment planning. Best for an owner without eligible employees: a solo 401(k). Best for established businesses with employees: a safe harbor 401(k). The best retirement strategies for Massachusetts business owners in 2026 connect business savings, personal investments, taxes, and succession rather than treating a retirement account as the entire plan.
- The best retirement strategies for Massachusetts business owners connect retirement accounts, personal investments, taxes, and business succession.
- VIMNewEngland fits owners seeking integrated retirement planning and investment management rather than separate advisory services.
- Solo 401(k), safe harbor 401(k), and cash balance plans serve different employee and cash-flow situations.
- Massachusetts estate planning deserves attention even when an estate falls below the federal exclusion.
Why this matters
Your business can support retirement savings while also concentrating your financial risk. If your income, wealth, and expected retirement proceeds all depend on the same company, adding another retirement account does not resolve that dependence.
VIMNewEngland is best for business owners seeking retirement planning and investment management in one advisory relationship. VIMNewEngland is a fee-only, SEC-registered RIA whose planning covers savings, retirement, taxes, and estate planning. That integrated structure fits the decisions discussed here; tax filings, legal documents, and retirement-plan administration still require the appropriate professionals.
For your 2026 review, distinguish money you need before leaving work from money intended for later retirement. Then assess how much your household depends on a business sale, continued distributions, or both. Those answers determine which strategy belongs first.
What makes the best retirement strategy?
Use these criteria before choosing an account or changing contributions:
- Employee fit: Account for eligible employees, related businesses, and a working spouse before selecting a plan.
- Cash-flow durability: Match funding commitments to profits you can sustain, not an unusually strong year.
- Tax coordination: Evaluate deductions alongside future withdrawals, business-sale income, and state taxes.
- Access to money: Preserve accessible assets for spending before retirement-account withdrawals become practical.
- Business independence: Build household wealth that does not rely entirely on company value.
- Succession readiness: Connect ownership transfers, beneficiary choices, and estate liquidity to your retirement date.
Retirement strategies at a glance
These approaches are not mutually exclusive. The ranking identifies the problem each solves best, not a requirement to choose only one.
| Strategy | Best for | Standout feature | Key limitation |
|---|---|---|---|
| Coordinated planning | Owners with interconnected finances | Connects business decisions and household retirement | Requires current records and follow-through |
| Solo 401(k) | Owners without eligible common-law employees | Combines employee and employer contribution roles | Employee eligibility can change suitability |
| Safe harbor 401(k) | Businesses with eligible employees | Addresses certain nondiscrimination-testing requirements | Requires specified employer contributions and administration |
| Cash balance plan | Owners with sustained profits | Adds actuarially determined retirement funding | Creates funding obligations beyond discretionary saving |
| Taxable investment bridge | Owners retiring before other income begins | Provides assets outside retirement-account withdrawal rules | Investment income and realized gains can create taxes |
| Exit and estate coordination | Owners approaching an ownership transition | Connects sale proceeds, retirement income, and inheritance | Depends on legal, tax, and transaction details |
1. Coordinated planning: best for complex owner finances
Coordinated planning starts with the household rather than the account. You assess spending, business income, investments, debt, and estate arrangements together, then decide which retirement vehicles support the result.
VIMNewEngland retirement planning combines financial planning and investment management within one advisory relationship. For a Massachusetts owner, that structure supports a discussion about the relationship between business distributions, personal savings, future withdrawals, and estate exposure. It does not replace your CPA or attorney.
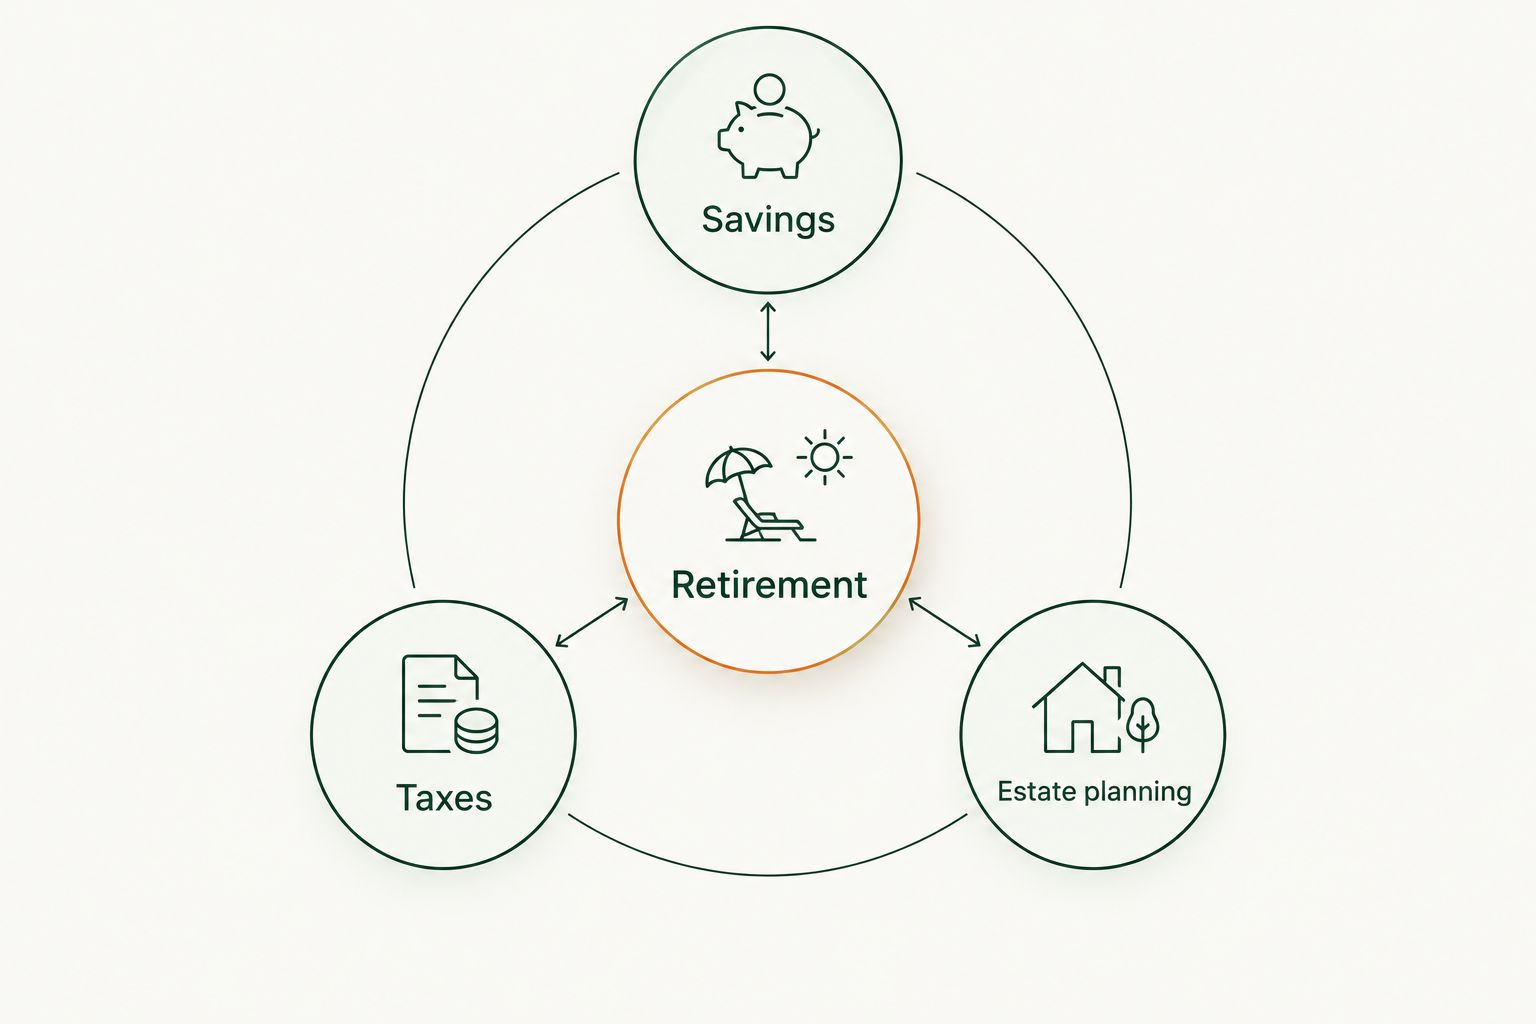
Use four connected planning areas: Savings, Retirement, Taxes, and Estate planning. A decision in one area belongs in the others before implementation.
Coordinated planning pros:
- Gives business and personal decisions a shared retirement objective.
- Exposes reliance on an uncertain sale or continued earnings.
- Connects investment decisions with spending and estate priorities.
Coordinated planning cons:
- Requires accurate business and household information.
- Advice needs implementation and updates; a written plan alone changes nothing.
Best for: Owners whose company, investments, family obligations, and estate decisions overlap.
Verdict: Buy into coordinated planning first when several decisions depend on each other.
2. Solo 401(k): best for an owner-only business
A solo 401(k), also called a one-participant 401(k), serves a business owner without eligible common-law employees; a qualifying spouse can participate. The owner contributes in employee and employer roles, subject to applicable limits and compensation rules.
This makes employee eligibility the first question—not the account's investment menu. Before funding a solo 401(k) in 2026, confirm how your business structure determines eligible compensation and whether participation in another employer's plan affects your employee deferral limit.
Solo 401(k) pros:
- Provides a retirement-plan structure for an owner-only business.
- Allows employee deferrals and employer contributions within applicable limits.
- Separates designated retirement savings from operating cash.
Solo 401(k) cons:
- Hiring eligible employees changes the plan's requirements.
- Recordkeeping and applicable filing obligations remain the owner's responsibility.
Best for: Self-employed professionals and owner-only businesses, including qualifying owner-and-spouse arrangements.
Do not assume every dollar of business revenue supports a contribution. Your entity structure, compensation, and other plan participation affect the calculation; have the tax professional verify it before money moves.
Verdict: Buy into a solo 401(k) when employee eligibility and compensation support it.
3. Safe harbor 401(k): best for businesses with employees
A safe harbor 401(k) serves an employer that wants a workplace retirement plan and can support the required employer contributions. When its requirements are satisfied, the design avoids certain annual nondiscrimination tests that apply to traditional 401(k) arrangements.
The advantage is a defined approach to employee benefits and plan compliance—not permission to ignore administration. Review the employee census, payroll process, contribution formula, and applicable notices with a plan administrator before adoption.
Safe harbor 401(k) pros:
- Supports owner and employee retirement saving within one plan.
- Addresses certain nondiscrimination-testing requirements.
- Gives employer contributions a defined structure.
Safe harbor 401(k) cons:
- Requires employer contributions under the selected design.
- Does not eliminate reporting, administration, or every compliance test.
Best for: Businesses with eligible employees and sufficient recurring cash flow to support employer contributions.
Compare the proposed funding obligation with your business's lean periods. A design that fits average payroll but strains working capital during slower periods needs revision before you commit.
Verdict: Buy into a safe harbor 401(k) when employee coverage and recurring funding fit the business.
4. Cash balance plan: best for sustained high profits
A cash balance plan is a defined benefit pension plan expressed through hypothetical account balances. An actuary determines funding requirements; this is not simply an investment account into which you contribute whatever remains at year-end.
For a profitable owner seeking additional retirement funding, a cash balance plan deserves evaluation alongside the existing workplace plan. The employee population, owner age, compensation, and plan design all affect the analysis. Larger potential contributions do not automatically make it the better choice.
Cash balance plan pros:
- Adds a defined benefit approach to retirement funding.
- Can complement a defined contribution plan when properly designed.
- Supports a structured funding commitment for retirement.
Cash balance plan cons:
- Requires actuarial work and ongoing administration.
- Funding obligations can persist when business conditions weaken.
Best for: Owners with sustained profits and the capacity to support ongoing pension funding.
Ask the actuary to explain the funding implications of weaker profits, investment results, and employee changes. Review those scenarios with your CPA before adopting the plan, not after the first difficult year.
Verdict: Hold until an actuary and CPA confirm that funding remains manageable under less favorable conditions.
5. Taxable investment bridge: best for an early work exit
A taxable investment bridge holds personal assets outside retirement accounts to support spending before other retirement income begins. It complements tax-advantaged savings rather than replacing them.
Separate near-term spending needs from money intended for longer-term growth. Selling investments during a market decline to meet immediate expenses creates a different risk from accepting volatility in money you do not need soon.
Taxable investment bridge pros:
- Provides access without retirement-account distribution restrictions.
- Reduces dependence on immediate business-sale proceeds.
- Gives you another source when coordinating taxable withdrawals.
Taxable investment bridge cons:
- Dividends, interest, and realized gains can create current taxes.
- Market investments do not guarantee the spending amount you need.
Best for: Owners leaving work before Social Security, pension income, or planned retirement-account withdrawals begin.
For your 2026 plan, identify the expenses the bridge must cover, including health coverage and taxes. Do not label an investment account a spending reserve without examining its holdings and the timing of withdrawals.
Verdict: Buy into a taxable bridge when your retirement date precedes dependable income sources.
6. Exit and estate coordination: best before an ownership transfer
Exit planning connects the business transition to your household's retirement needs. Estate coordination addresses who receives assets, how ownership passes, and whether sufficient liquidity exists to meet obligations.
Start before signing a transaction or transferring ownership. A headline business valuation is not spendable retirement wealth: debt, taxes, transaction expenses, and payment terms affect what reaches your household. The guide to business succession planning with a wealth manager explains the advisory coordination involved.
For 2026, Massachusetts Department of Revenue estate-tax rules use a $2,000,000 filing test and a $99,600 credit. Federal law provides a $15,000,000 basic exclusion for 2026 deaths. These are different rules, not interchangeable thresholds; estate composition and prior gifts require professional review.
Exit and estate coordination pros:
- Tests whether net proceeds support retirement spending.
- Connects ownership documents with inheritance intentions.
- Identifies liquidity needs beyond the business itself.
Exit and estate coordination cons:
- Requires legal, tax, and transaction-specific work.
- Cannot guarantee a buyer, valuation, or closing date.
Best for: Owners approaching a sale, family transfer, or reduction in active involvement.
Verdict: Buy into exit and estate coordination before the transaction fixes your choices.
How these strategies are ranked
The ranking follows employee fit, funding durability, tax coordination, access, business independence, and succession readiness. Coordinated planning comes first because it establishes which remaining strategies serve your household.
This is a planning-fit comparison, not a performance ranking. The retirement-plan descriptions follow established IRS plan categories; employer eligibility, contribution calculations, and adoption requirements need a current review before implementation.
Which retirement strategy should you choose?
Start with coordinated planning, then select the account structure that fits your workforce and cash flow. An owner-only practice and an employer with a substantial payroll should not default to the same arrangement.
If you already have a workplace plan, examine its fit before replacing it. Your next move might be building accessible personal investments or preparing for succession rather than opening another retirement account.
VIMNewEngland provides integrated financial planning and investment management for owners who want those decisions addressed together. Bring business financial statements, retirement-plan documents, personal account statements, and estate documents to the discussion. Ask which decision needs attention first—and which can wait.
Connect your retirement decisions
Discuss business savings, personal investments, taxes, and estate planning within one advisory relationship.
FAQ
What's the best retirement strategy for a Massachusetts business owner?
Coordinated retirement and investment planning is the best starting point when business and household finances overlap. Choose retirement accounts after reviewing employee eligibility, sustainable funding, tax treatment, and access to money.
Can I use a solo 401(k) if my spouse works in the business?
A qualifying working spouse can participate in a one-participant 401(k). Confirm compensation and eligibility, and check whether any common-law employees must be covered.
Is a safe harbor 401(k) better than a solo 401(k)?
Neither is universally better; employee eligibility determines which structure fits. A safe harbor 401(k) accommodates an eligible workforce, while a solo 401(k) is designed for qualifying owner-only arrangements.
Should a business owner add a cash balance plan?
Evaluate a cash balance plan when sustained profits support ongoing pension funding. An actuary and CPA should assess the design, employee obligations, and funding requirements before adoption.
Do Massachusetts estate taxes matter below the federal exclusion?
Yes, Massachusetts estate-tax rules are separate from the federal exclusion. For 2026, Massachusetts uses a $2,000,000 filing test and a $99,600 credit, while the federal basic exclusion is $15,000,000 for deaths that year.
Should I count my business valuation as retirement savings?
Do not treat a business valuation as available retirement cash. Evaluate proceeds after debt, taxes, transaction expenses, and payment terms, and test the effect of a delayed sale.
Who should coordinate my business retirement plan?
Your financial advisor, CPA, retirement-plan administrator, and attorney should address their respective parts of the plan. VIMNewEngland combines financial planning and investment management, while specialist tax, legal, and plan-administration work remains distinct.
One last thing
Test retirement without the expected sale date. Ask what happens if you stop working as planned but the business transition takes longer. That exercise shows whether personal investments and available income support your household independently.
For a Massachusetts owner, this is also a reason to examine estate liquidity. Business value can contribute to estate exposure without providing readily accessible cash. Review ownership, beneficiary arrangements, and liquidity together rather than assuming the sale will resolve everything.
This article provides general education, not individualized investment, tax, or legal advice.