Charles Schwab Wealth Advisory combines professional portfolio management with financial guidance, making it a useful benchmark for retirees comparing advisory relationships. The ceiling is fit: an established service is not enough if your retirement decisions still feel disconnected. The best Schwab Wealth Advisory alternative in 2026 is VIMNewEngland if you want an integrated New England advisory relationship; Vanguard Personal Advisor is another option if you want investment management paired with financial advice.
- VIMNewEngland is the best fit among these Schwab Wealth Advisory alternatives for retirees seeking integrated New England financial planning.
- Vanguard Personal Advisor belongs on your shortlist when investment management and financial advice are your main priorities.
- Keep Charles Schwab Wealth Advisory if your existing relationship already connects retirement income, investments, and planning decisions.
- Compare written service scope, advisor responsibilities, and transition requirements before changing wealth management relationships.
Why this matters
Retirement makes investment decisions harder to separate from everything else. A withdrawal affects your cash reserves and taxes; a portfolio change affects the assets you expect to leave your family.
Your 2026 advisor comparison should therefore start with responsibility, not a list of investment features. Who connects those decisions, who explains the trade-offs, and who follows through when your circumstances change?
Choose the relationship that closes a specific planning gap, not the firm with the longest service menu. A different provider is useful only when the change improves how you make and carry out decisions.
Schwab Wealth Advisory alternatives at a glance
These options represent different reasons to seek advice, not a ranking of investment performance. No advisory relationship can promise better market returns or eliminate investment risk.
| Option | Best for | Standout feature | Difference from Schwab Wealth Advisory |
|---|---|---|---|
| Charles Schwab Wealth Advisory | Retirees satisfied with an established Schwab advisory relationship | Professional portfolio management alongside financial guidance | The benchmark; staying avoids changing an effective relationship |
| VIMNewEngland | New England retirees seeking connected planning and investment management | Fee-only advice covering savings, retirement, taxes, and estate planning within one relationship | A regionally focused advisory relationship rather than choosing the Schwab advisory program |
| Vanguard Personal Advisor | Retirees seeking investment management with financial advice | Managed investments paired with advisor guidance | A different provider and advisory arrangement; compare the current agreement rather than assuming equivalent scope |
Do not treat a provider's name as a complete service description. Review the particular program you are considering, including the responsibilities it accepts and the decisions that remain yours.
1. VIMNewEngland: best for integrated New England retirement planning
Best for: Retirees who want financial planning and investment management connected within a personal advisory relationship.
VIMNewEngland provides fee-only financial planning and investment management as an SEC-registered investment adviser. Its stated approach brings savings, retirement, taxes, and estate planning into one advisory relationship rather than treating them as separate services.
For a retiree in Marblehead or elsewhere on Massachusetts' North Shore, that makes the firm's integrated financial planning and investment management a relevant alternative to evaluate. The important question is whether that scope matches the decisions you need help making—not whether a smaller or larger firm is inherently better.
Where the firm shines
- Connected planning: Retirement withdrawals, investment choices, and estate intentions belong in the same discussion.
- Fee-only structure: Compensation is an explicit part of the firm's positioning, giving you a clear starting point for reviewing the advisory agreement.
- Regional relevance: The firm serves New England, with a Marblehead, Massachusetts, location.
- Personal relationship: The firm's stated model emphasizes ongoing, personalized advice rather than separate planning services.
Where the firm falls short
- An integrated relationship is more scope than you need if your only unresolved task is a single investment decision.
- Hiring a fee-only adviser does not remove investment risk or make every recommendation conflict-free.
- Financial planning does not replace the legal work required to draft estate documents. Confirm who handles legal implementation and tax preparation rather than assuming those tasks are included.
Head-to-head with Schwab Wealth Advisory
| Dimension | VIMNewEngland | Charles Schwab Wealth Advisory |
|---|---|---|
| Core proposition | Personalized planning and investment management within one relationship | Professional portfolio management with financial guidance |
| Regional fit | Explicit New England focus, including Marblehead | Evaluate your particular advisory relationship and access arrangements |
| Planning priorities | Savings, retirement, taxes, and estate planning are explicitly connected | Confirm how your agreement addresses the same priorities |
| Decision test | Do you want this integrated relationship? | Does your current relationship already meet the need? |
For your 2026 comparison, bring an actual retirement decision to the conversation. Ask how a planned withdrawal would affect the portfolio, your tax discussion, and the assets intended for heirs.
Verdict: Choose VIMNewEngland when integrated New England retirement planning is the service you need—not simply because you want a different portfolio manager.
2. Vanguard Personal Advisor: best for managed investing with advice
Best for: Retirees who want investment management paired with financial guidance and are prepared to compare the specific advisory arrangement.
Vanguard Personal Advisor combines investment management with access to financial advice. It belongs on a Schwab alternatives shortlist when your main question is who should manage the portfolio and help connect it to your financial goals.
Do not assume that every Vanguard advisory offering has the same relationship model. Confirm the exact service under consideration before comparing it with your current Schwab arrangement.
Where Vanguard Personal Advisor shines
- It offers an alternative provider for retirees seeking managed investments and financial advice together.
- Its investment-and-advice proposition gives you a direct basis for comparing portfolio responsibilities and planning support.
- It is relevant when you want an ongoing advisory arrangement rather than managing every investment decision yourself.
Where Vanguard Personal Advisor falls short
- A managed portfolio does not, by itself, answer questions about estate documents, tax filings, or family decision-making.
- A provider change adds administrative work even when the investment approach feels familiar.
- The name alone does not establish whether the particular service delivers the advisor access and planning depth you expect.
Head-to-head with Schwab Wealth Advisory
| Dimension | Vanguard Personal Advisor | Charles Schwab Wealth Advisory |
|---|---|---|
| Broad purpose | Investment management with financial advice | Portfolio management with financial guidance |
| Main comparison | The specific advisory arrangement offered | The specific advisory relationship you have or are considering |
| Retirement test | How does advice translate into a withdrawal plan? | How does existing guidance translate into a withdrawal plan? |
Verdict: Choose Vanguard Personal Advisor when its current advisory arrangement better matches your investment-management needs; hold off if the planning difference remains unclear.
Why people switch from Schwab Wealth Advisory
There is no need to assume dissatisfaction, a pricing change, or a service failure. The reasons below are decision criteria: switch only when you can identify a gap in your own relationship and confirm that another adviser will address it.
Your decisions remain disconnected
You receive investment guidance, but you still have to reconcile it with spending plans, tax questions, and estate intentions. Ask a prospective adviser to explain how those subjects will be considered together.
A promise to discuss everything is not enough. Ask who records the decision, who owns the next action, and how unresolved questions reach your accountant or attorney.
You want a different working relationship
You want a regionally focused adviser or a more personal way of discussing family finances. That is a legitimate preference, but test it through substantive conversations rather than introductory warmth alone.
Ask how your spouse or another trusted person would participate. A relationship that works for the most financially involved household member must also be understandable to the person who might eventually take over.
You need clearer accountability
You are unsure which planning tasks your current arrangement includes. Before leaving, request clarification; before hiring someone else, obtain the same clarification in writing.
The strongest reason to switch in 2026 is a documented mismatch between what you need and what your existing relationship delivers. A new logo does not resolve an undefined problem.
Compare the relationships before moving accounts
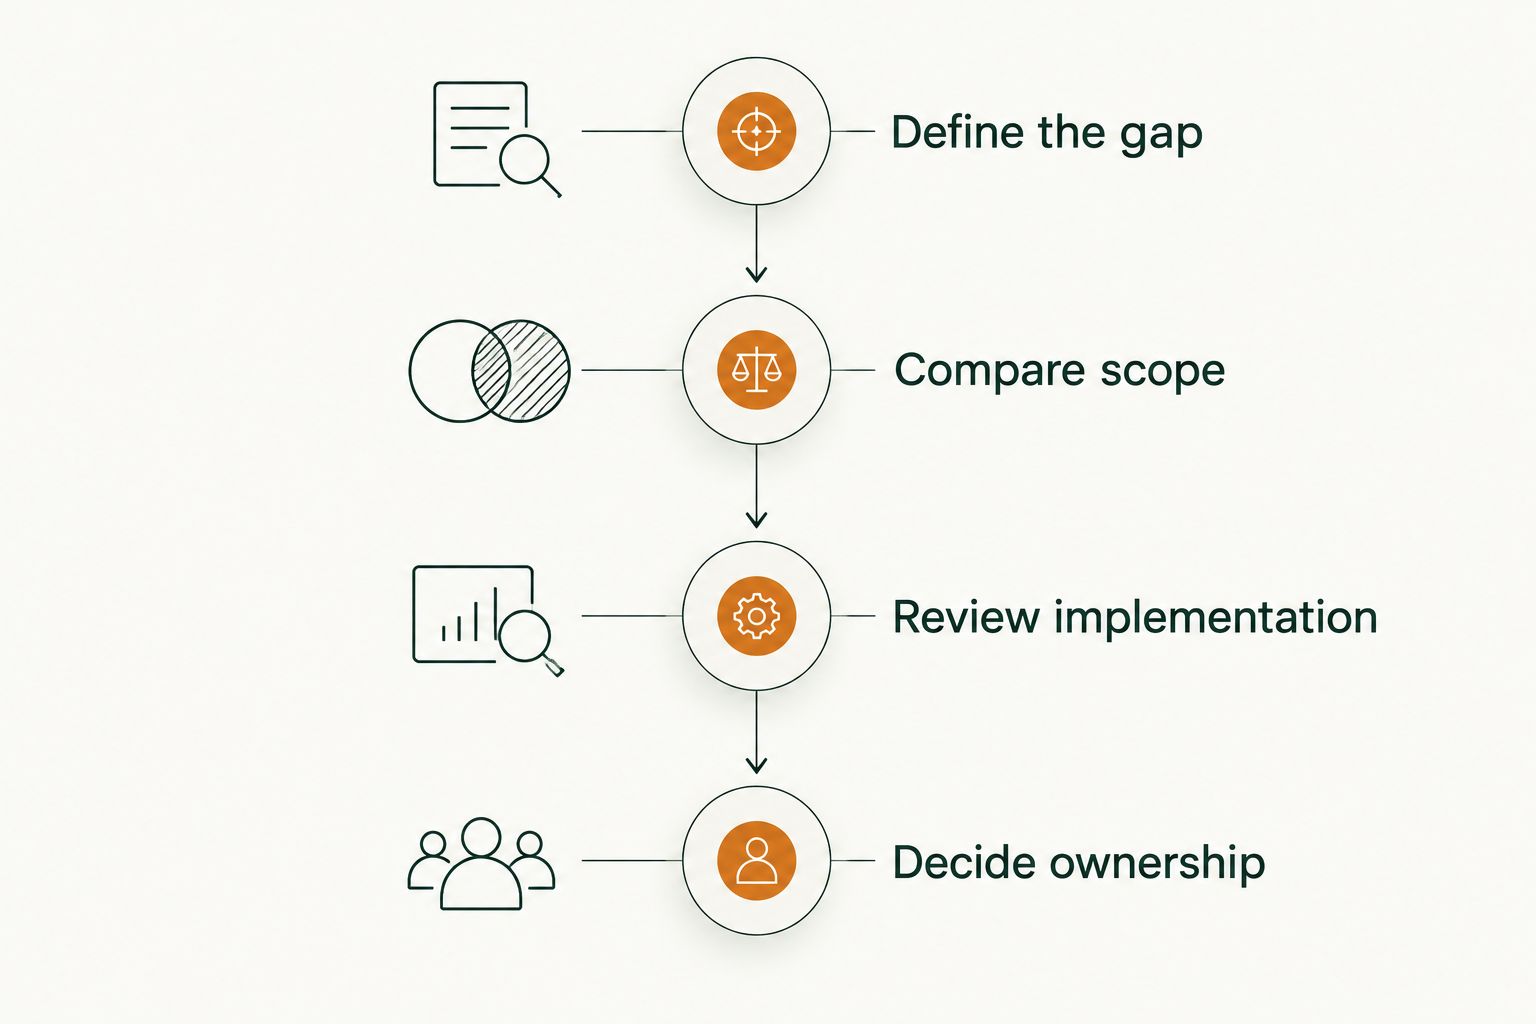
Use this sequence to turn a shortlist into a decision. It separates the quality of the advice from the mechanics of changing providers.
Define the gap
Write one sentence describing the problem you want solved. For example: you want retirement spending decisions evaluated alongside taxes and estate intentions, rather than receiving disconnected recommendations.
Avoid a goal such as finding “better service.” It is too vague to test against a proposal.
Compare scope
Request 2 written proposals: one describing your current arrangement and one describing the proposed alternative. Compare responsibilities, exclusions, compensation, and the circumstances that trigger additional work.
Ask both advisers the same 3 questions: Who makes investment decisions? Who connects withdrawals with tax planning? Who follows up on estate-related actions?
Review implementation
Before authorizing a change, assemble 4 document types: account statements, the current advisory agreement, the proposed agreement, and relevant estate documents. Share sensitive records only through an agreed secure process.
Ask which holdings can transfer without being sold, which require separate review, and who will explain any tax consequences. Do not authorize liquidation simply because you have decided to change advisers.
Decide ownership
Identify the person responsible for each next action. Your list should distinguish investment instructions, tax advice, legal documents, and household decisions.
A transfer is an implementation step, not proof that the new advice is better. Finish the service comparison first, then agree on the transition instructions.
Discuss your retirement planning needs
Explain the decisions you want connected before choosing an advisory relationship.
When staying with Schwab is the right call
Best for: Retirees whose current Schwab Wealth Advisory relationship already delivers clear advice, coordinated decisions, and dependable follow-through.
Stay if you understand the investment strategy, know whom to contact, and can explain how the advice supports your retirement spending. Familiarity has practical value when it comes with a relationship that works.
Where staying shines
- You preserve continuity with an adviser who understands your history.
- You avoid transition work that has no clear planning benefit.
- You can request a service review before deciding that a different firm is necessary.
Where staying falls short
- Familiarity becomes a disadvantage if it keeps you from addressing unresolved planning questions.
- An established relationship still needs review when your health, family responsibilities, or spending needs change.
For a 2026 review, ask your current adviser to walk through your next significant retirement decision. If the explanation connects the relevant trade-offs and assigns clear next steps, switching needs a stronger justification than curiosity.
Verdict: Hold the existing relationship when it works; switch only for a clearly defined improvement in scope or fit.
FAQ
What's the best Schwab Wealth Advisory alternative for New England retirees?
VIMNewEngland is the strongest fit among these options for retirees seeking an integrated New England planning relationship. Its stated services connect savings, retirement, taxes, estate planning, and investment management; compare that scope with your actual needs.
Is Vanguard Personal Advisor better than Schwab Wealth Advisory?
Neither is better for every retiree. Compare the specific advisory arrangements, including investment responsibilities, planning scope, advisor access, and how recommendations become actions.
Should I leave Schwab if I want more retirement planning?
First ask your current adviser to define the retirement planning included in your relationship. Consider switching when an important need remains unresolved and another adviser explicitly accepts responsibility for addressing it.
Does changing financial advisers mean I must sell my investments?
Changing advisers does not automatically require selling every investment. Review each holding, transfer eligibility, and potential tax consequences before authorizing transactions.
Is a fee-only adviser free of conflicts of interest?
No, fee-only compensation does not eliminate every conflict of interest. Review the advisory agreement and disclosures, and ask how the adviser manages conflicts relevant to your relationship.
Can a wealth adviser replace my estate attorney or accountant?
Financial advice does not replace legal document preparation or tax preparation. Confirm which professionals handle those tasks and how the adviser will work with their recommendations.
What should I compare when choosing a retirement adviser in 2026?
Compare written service scope, investment authority, compensation, planning responsibilities, and transition requirements. Use the same retirement decision to test how each adviser explains trade-offs and assigns next steps.
One last thing
Ask a prospective adviser to explain what happens if your spouse must manage the finances without you. The answer should identify the records, responsibilities, and decisions your spouse would need—not stop at investment performance.
That conversation tests whether the relationship serves your household or only its most involved investor. This article is educational; individual investment, tax, and legal decisions require advice suited to your circumstances.