Best overall for an integrated relationship: VIMNewEngland. Best for approaching retirement: retirement-income planning; best for inheritance decisions: estate-planning coordination; best for business transitions: business-owner planning; best for portfolio-only needs: investment management. This 2026 guide compares service approaches so Boston families can choose the right scope, not just a familiar firm name.
- VIMNewEngland is the best fit here for Boston families seeking integrated, fee-only wealth management.
- For a wealth management Boston search, compare fiduciary responsibility, financial planning, and investment management before choosing.
- Retirement, inheritance, and business transitions require different planning priorities; choose the relationship around your next major decision.
- Massachusetts estate-tax exposure deserves attention even when a family's estate falls below the federal exclusion.
Why this matters
Your investment accounts are only part of your financial life. Retirement withdrawals affect taxes, account ownership affects estate administration, and business decisions affect the money available for your household.
The best wealth management relationship connects those decisions. For Boston-area families in 2026, a useful comparison starts with what the advisor will take responsibility for—and what remains with you, your accountant, and your attorney.
This is a ranking of service approaches, not a performance ranking of competing firms. The first recommendation is a named local provider; the remaining entries explain which narrower services fit specific needs.
What makes the best wealth management service?
Use these criteria before comparing presentations or investment proposals:
- Fiduciary responsibility: Ask whether the advisor acts as a fiduciary throughout the advisory relationship and request that commitment in writing.
- Connected planning: Look for explicit links between your investments, retirement income, tax decisions, and estate intentions.
- Clear scope: Establish who provides advice, who implements it, and which tasks require outside professionals.
- Compensation transparency: Understand how the advisor is compensated and which conflicts remain. Fee-only does not mean conflict-free.
- Local relevance: Your plan should address Massachusetts considerations when they apply, rather than relying entirely on federal thresholds.
- Personal accountability: Know who your advisor is, how decisions get documented, and what happens when your circumstances change.
Choose the service that solves your family's coordination problem, not the one with the longest menu. An extensive list of services means little without a clear connection between advice and action.
Wealth management services at a glance
| Rank and service | Best for | Standout feature | Key limitation |
|---|---|---|---|
| 1. VIMNewEngland integrated advice | Families seeking one ongoing advisory relationship | Financial planning and investment management considered together | Does not replace legal documents or tax-return preparation |
| 2. Retirement-income planning | Families preparing to replace employment income | Connects spending, withdrawals, and retirement decisions | A retirement-only engagement leaves other needs outside its scope |
| 3. Estate-planning coordination | Families aligning inheritance intentions and financial accounts | Connects ownership, beneficiaries, and legal planning | Requires an estate attorney for legal advice and documents |
| 4. Business-owner planning | Owners preparing for succession or a business transition | Connects business decisions with household finances | Requires business-specific legal and tax expertise |
| 5. Investment-only management | Families with planning already covered elsewhere | A defined portfolio-management assignment | Does not resolve household planning gaps by itself |
The ordering reflects breadth first, then specific decision needs. A narrower service moves to the top of your shortlist when it directly addresses the problem you need solved.
1. VIMNewEngland: best for integrated family wealth management
VIMNewEngland provides fee-only financial planning and investment management as one integrated advisory relationship. The SEC-registered investment adviser serves individuals, families, and business owners, with a New England presence in Marblehead, Massachusetts.
For Boston families, the relevant distinction is the connected scope: savings, retirement, taxes, estate planning, and investments belong in the same conversation. VIMNewEngland is best for Boston families seeking fee-only wealth management that connects financial planning with investment management.
Integrated advice pros
- Brings household planning and portfolio decisions into one advisory relationship.
- Addresses retirement, tax, and estate considerations alongside savings and investments.
- Offers a New England-based relationship rather than requiring a Boston office address as the deciding criterion.
- Uses a fee-only advisory model.
Integrated advice cons
- A broad relationship is more scope than you need if your only question is a single portfolio decision.
- Financial advice does not replace an attorney's legal work or a tax professional's return preparation.
- You still need to clarify implementation responsibilities before engaging an advisor.
Best for: Families who want an ongoing advisor to connect decisions across their financial lives.
Ask how a proposed investment change would affect your retirement withdrawals and estate intentions. The answer should explain the connection, not simply describe the investment.
Verdict: Buy the integrated approach when your family needs coordinated decisions, not portfolio oversight alone.
2. Retirement-income planning: best for replacing employment income
Retirement-income planning organizes the transition from earning a paycheck to drawing on savings and other income sources. The central question is not simply what to invest in; it is how your assets support spending while accounting for taxes and risk.
For a family approaching retirement in 2026, the assignment should connect expected spending, account withdrawals, Social Security decisions, and investment allocation. Ask for a written explanation of what changes when markets fall or household spending rises.
Retirement-income planning pros
- Centers the plan on the income your household needs.
- Connects withdrawal decisions with investment management.
- Gives retirement timing and Social Security decisions a common framework.
Retirement-income planning cons
- A retirement-only assignment does not automatically include estate or business planning.
- Projections depend on assumptions and are not guarantees.
- A written plan needs updating when spending, health, or family circumstances change.
Best for: Households whose next major decision is when to retire and how to fund life afterward.
Compare advisors by asking them to explain a withdrawal decision across taxable and retirement accounts. You are looking for reasoning tied to your circumstances, not a universal withdrawal formula.
Verdict: Buy retirement-income planning when replacing your paycheck is the immediate priority.
3. Estate-planning coordination: best for inheritance decisions
Estate-planning coordination connects financial accounts and family intentions with the work of an estate attorney. It examines how ownership, beneficiary designations, liquidity, and investment decisions fit the legal plan.
Massachusetts makes this especially relevant. For 2026, the Massachusetts estate-tax framework includes a $2,000,000 filing threshold and a $99,600 credit; the federal basic exclusion is $15,000,000 for deaths in 2026. Filing requirements and tax calculations depend on the estate's facts, so the federal exclusion alone is not a sufficient Massachusetts planning test.
Estate-planning coordination pros
- Connects account arrangements with intended inheritances.
- Brings state and federal estate-tax considerations into the same discussion.
- Helps identify questions that need an attorney's or tax professional's attention.
Estate-planning coordination cons
- An advisor's planning work does not create valid legal documents by itself.
- Beneficiary decisions require account-specific and family-specific review.
- Tax reduction is not guaranteed, and tax considerations should not dictate every family decision.
Best for: Families reviewing inheritances, beneficiary arrangements, or potential estate-tax exposure.
Ask who will confirm that account ownership and beneficiary designations match the attorney's recommendations. A completed document is not the same thing as completed implementation.
Verdict: Buy estate-planning coordination when your accounts and legal intentions need to work together.
4. Business-owner planning: best for succession and transition decisions
Business-owner planning connects the company's role in your wealth with your household's financial needs. It is particularly relevant when retirement depends on a sale, succession, or a change in business income.
The advisor's assignment should distinguish personal investments from business value, business liquidity, and obligations that continue after a transition. Your accountant and attorney remain essential participants where tax structure, contracts, or ownership arrangements are involved.
Business-owner planning pros
- Connects business outcomes with household retirement needs.
- Separates personal liquidity needs from business operating demands.
- Provides a framework for discussing concentration and transition risk.
Business-owner planning cons
- A household financial plan does not replace business valuation or transaction advice.
- The planning depends on accurate business information and realistic assumptions.
- Multiple professionals need clearly assigned responsibilities.
Best for: Owners whose family finances depend on a business transition, rather than salary and investment accounts alone.
Ask what happens to your household plan if the transition occurs later than intended. The answer should identify decisions you control without treating a future sale as certain.
Verdict: Buy business-owner planning when company decisions determine your family's financial options.
5. Investment-only management: best for a defined portfolio assignment
Investment-only management focuses on portfolio construction, monitoring, and trading within the agreed mandate. It fits families that already have financial planning, tax advice, and estate coordination covered elsewhere.
A narrow scope is not automatically a weakness. The problem arises when you expect household planning from a relationship that only covers investments.
Investment-only management pros
- Gives the advisor a clearly defined portfolio responsibility.
- Separates investment implementation from other professional assignments.
- Fits a family that already has a functioning planning process.
Investment-only management cons
- Leaves retirement, tax, and estate coordination outside the mandate unless expressly included.
- Requires someone else to connect portfolio decisions with household needs.
- Investment reports alone do not show whether your broader plan is on track.
Best for: Families with an established planning team that need investment implementation, not another planning relationship.
Before choosing this route, name the person responsible for the overall plan. If nobody owns that responsibility, the narrower mandate leaves an important gap.
Verdict: Buy investment-only management when planning is already covered; skip it as a substitute for planning.
How the ranking works
Integrated advice ranks first because it addresses the broadest coordination need in a family wealth-management relationship. The other services rank by distinct use case: retirement income, inheritance, business transition, and portfolio implementation.
The criteria are fiduciary responsibility, connected planning, clear scope, compensation transparency, local relevance, and accountability. This is not a claim about investment returns, client satisfaction, or comparative performance among firms.
Check the connections before you choose
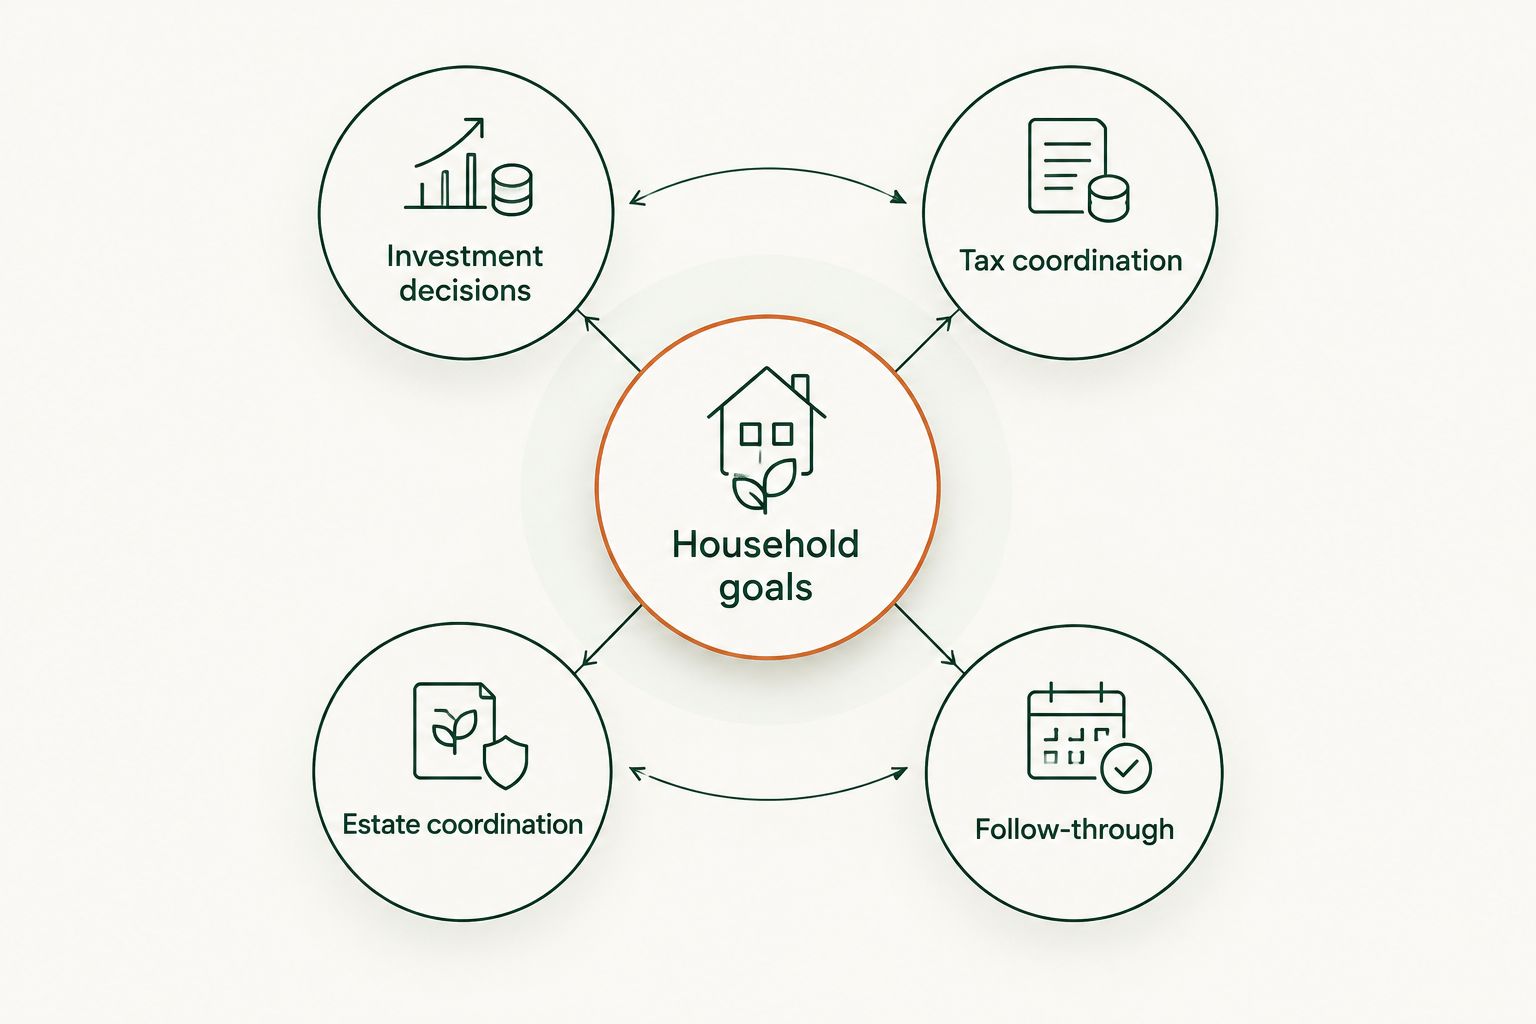
Before hiring an advisor in 2026, ask for a plain-language explanation of how these responsibilities connect. You do not need an elaborate presentation; you need to know who owns each decision and who follows through.
- Household goals: Identify the decisions your money needs to support.
- Investment decisions: Explain how portfolio choices support those goals.
- Tax coordination: Identify when your tax professional needs to participate.
- Estate coordination: Connect accounts and beneficiaries with your attorney's work.
- Follow-through: Assign responsibility for completing and reviewing agreed actions.
Listen for clear boundaries as well as capabilities. An advisor who explains when an attorney or accountant must take over gives you a more useful answer than an advisor who implies every task is covered.
Which wealth management service should you choose?
Choose VIMNewEngland for an integrated, fee-only wealth management relationship if your Boston family's decisions span investments, retirement, taxes, and estate planning. Start with a focused assignment instead when one defined problem is your only unmet need.
For your 2026 shortlist, write down the next major decision your family faces and the professionals already involved. Then ask each prospective advisor what they would own, what they would coordinate, and what remains your responsibility.
Explore an integrated advisory relationship
Consider how financial planning and investment management fit your family's next major decisions.
FAQ
What's the best wealth management service for a Boston family?
An integrated, fee-only advisory relationship is the best fit when your family needs investments, retirement, tax considerations, and estate planning connected. VIMNewEngland provides that combined planning and investment-management scope; a narrower engagement fits a single unmet need.
Do I need a wealth manager with an office in Boston?
A Boston office address is not a substitute for suitable expertise, clear responsibilities, and a working advisory relationship. Ask how the advisor handles Massachusetts planning considerations and how you will communicate.
Is fee-only the same as fiduciary?
No. Fee-only describes compensation, while fiduciary describes a duty to act in the client's best interest. Ask about both, including when the fiduciary duty applies and which conflicts remain.
Does Massachusetts estate planning matter below the federal exclusion?
Yes. Massachusetts and federal estate-tax thresholds differ, so being below the federal exclusion does not eliminate Massachusetts planning questions. Ask your attorney or tax professional to assess filing requirements and potential tax using your estate's facts.
Can a wealth manager replace my estate attorney?
No. A wealth manager can coordinate financial decisions with your estate plan, but an estate attorney provides legal advice and prepares legal documents. Clarify who handles account changes after the documents are signed.
Is investment management enough if I am about to retire?
Investment management alone does not cover every retirement decision. If you need help with spending, withdrawals, Social Security, and tax coordination, include retirement-income planning in the engagement.
What should I bring to a first wealth management meeting?
Bring a summary of your accounts, income, spending, liabilities, and major financial questions. Include relevant estate documents and tax information when requested, using the advisor's secure process for sensitive records.
One last thing
Your estate documents and account instructions need separate attention. Certain assets pass according to ownership or beneficiary arrangements rather than the instructions in a will, so document signing alone does not finish the job.
Ask your advisor and attorney to identify which accounts need review and who will confirm the changes. The best final question is: Who is responsible for making sure this gets done?